A dispute with your insurer: organise the reasons before escalating
A refusal letter can be frustrating, but an effective challenge starts with the exact reason for refusal and the clause relied upon. A disagreement over facts needs different evidence from a disagreement over interpretation.

The question that matters
A refusal letter can be frustrating, but an effective challenge starts with the exact reason for refusal and the clause relied upon. A disagreement over facts needs different evidence from a disagreement over interpretation.
Distinguish refusal of the entire claim from a disagreement about part of the settlement. The evidence needed to show that an event is insured can differ from evidence about repair cost, depreciation or the extent of damage. A clear problem statement prevents several separate issues being conflated in one emotional response.
Build the evidence
Request the decision in writing and identify the relevant policy, edition of terms and claimed event date. Assemble the claim submission, invoices, expert reports and correspondence. Create a list of points you accept, points you dispute and documents still missing.
Build a claim map with the accepted facts, disputed facts and clause references. Number the supporting documents so the reader can follow each point. Where a technical conclusion is disputed, explain which observation you challenge and why, rather than simply stating that the insurer’s expert must be wrong.
A hypothetical case
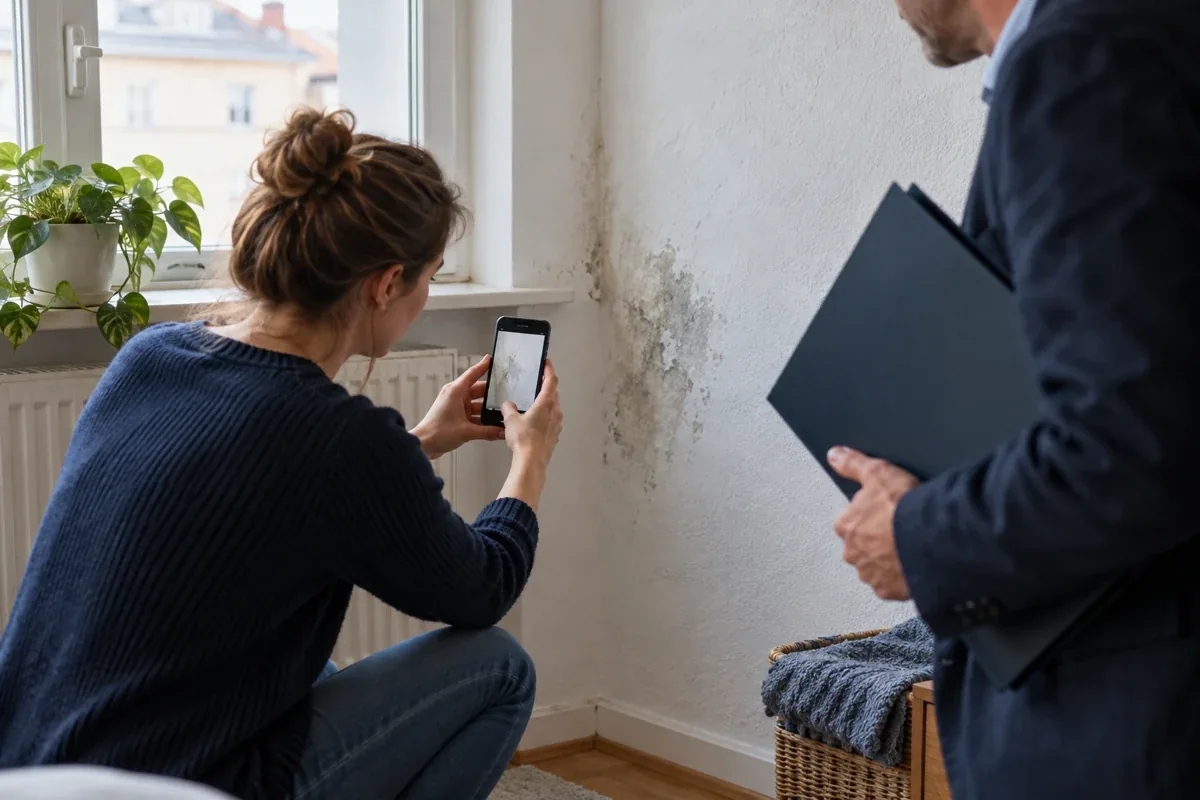
An insurer rejects a water-damage claim because it considers the cause excluded. A repair invoice alone may not resolve that causal question. In this hypothetical case, the useful evidence could be the technical report establishing how the damage occurred.
For the water damage example, separate the origin of the water from the amount needed to restore the property. A report may address causation while estimates address cost. If both are challenged, request a strategy that covers each question without commissioning duplicate investigations before cost approval is clear.
Compare the right conditions
Compare insurance-dispute cover, exclusions involving your legal-protection provider or group, expert funding and conflict procedures. Ask which deadlines apply to challenging the decision and who is responsible for preserving them.
Ask how the legal-protection contract handles disagreement involving another insurer within the same group, and what the actual conflict procedure provides. Independence claims in advertising should not replace examination of the applicable clause. Request a precise explanation for your configuration of insurers.
Limits and uncertainties
The fact that a decision is unfavourable does not establish that it is wrong. Legal protection may assess merits and contractual scope before financing action. Public reporting about insurer disputes provides context, not proof concerning your own claim.
Keep ordinary claims obligations running while the dispute is reviewed. Avoid destroying damaged items or carrying out non-urgent work without understanding evidence requirements. Equally, necessary safety or loss-mitigation measures need appropriate handling; seek specific guidance instead of assuming all work must stop until funding is agreed.
Your practical next step
Send a concise factual challenge with numbered points and supporting documents. Contact the legal insurer if the domain is covered, and obtain approval for external costs. Keep dispute handling separate from a decision about switching cover for future years.
If the first explanation remains unsatisfactory, use the documented review or complaint route and obtain qualified advice where needed. State the outcome sought and attach the relevant evidence. A disciplined escalation is easier to evaluate than repeated broad complaints that never identify the contractual or factual point at issue.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.