
Earn francs, spend euros: build a household currency policy
Make exchange-rate uncertainty manageable without trying to predict the market.
Start with obligations, not forecasts
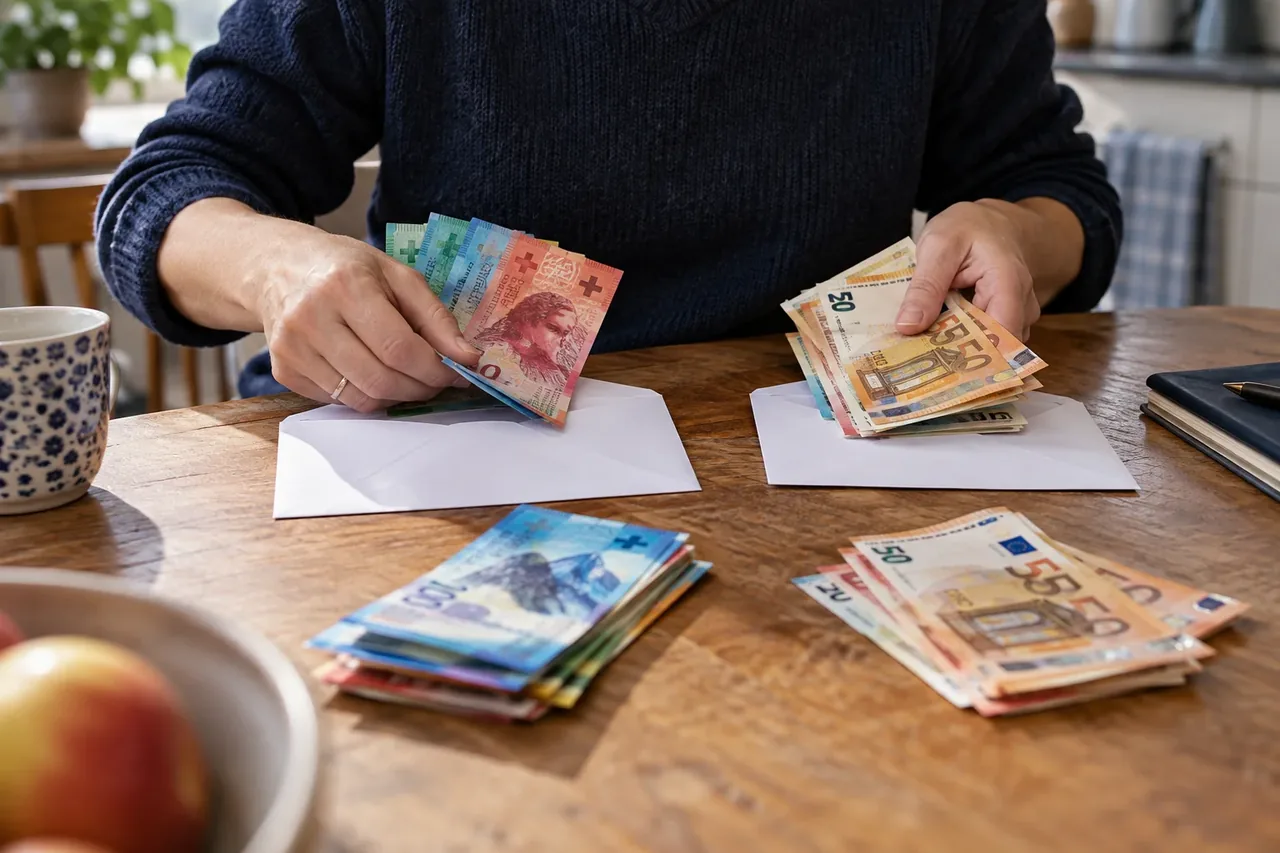
A cross-border salary and a French household budget create a mismatch between the currency of income and the currency of bills. Predicting the next exchange rate is less useful than knowing how many euros you need each month. List housing, utilities, childcare, taxes and loan payments separately from discretionary spending. Then identify which obligations are already in francs. The resulting currency map shows the part of income that must be converted and the part that can remain aligned with Swiss expenses.
Measure the full conversion cost
Compare exchange services using the same amount, quotation time and destination account. Include the spread, transfer fee, receiving-bank charge and any subscription cost. A service advertised as fee-free may still earn money through its quoted rate. For a recurring household transfer, test the net euros actually credited rather than comparing slogans. Document how the service handles delayed transfers, failed payments and beneficiary changes. These operational details matter when a mortgage debit has a fixed date.
Hypothetical sensitivity test
Suppose CHF 5,000 is converted monthly. At an illustrative rate of EUR 1.02 per franc, it produces EUR 5,100 before fees; at EUR 0.96, it produces EUR 4,800. The EUR 300 difference is a budget stress, not a forecast. Calculate whether your household absorbs that change without missed payments. Repeat the exercise on your actual required transfer amount and avoid attaching a probability to invented rates. Their purpose is to expose dependence, not predict direction.
Choose a repeatable rule
One approach is to convert the next month’s essential euro bills on a planned date and maintain a euro reserve for disruptions. Another is to split a transfer across dates to reduce dependence on one quote. Neither guarantees a better average rate. The appropriate rule is the one that makes obligations predictable and can be followed during a busy month. Keep long-term investment choices separate from the operational money needed for next week’s direct debits.
Align records with declarations
Bank conversion rates used for spending and the tax conversion method required for a declaration are different concepts. Keep transfer receipts, but use the current French administration’s instructions when calculating reportable Swiss salary. Do not assume your preferred exchange app determines the fiscal amount. Similarly, separate a currency gain in savings from employment income when asking for tax classification. This article offers budgeting principles; it does not prescribe a tax treatment for an investment or a foreign account.
Review debt and reserves together
A large debt denominated differently from salary magnifies currency exposure. Ask a lender to illustrate repayments under alternative exchange assumptions before accepting the apparently cheaper currency. Consider what happens after unemployment, retirement or a move changes the income currency. Review the policy annually with the household budget and document the reason for changing it. The practical goal is a reserve and conversion process that protects essential payments while leaving room for savings, rather than a permanent attempt to time the market.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


