
The first day after a liability incident: preserve facts and coordinate the response
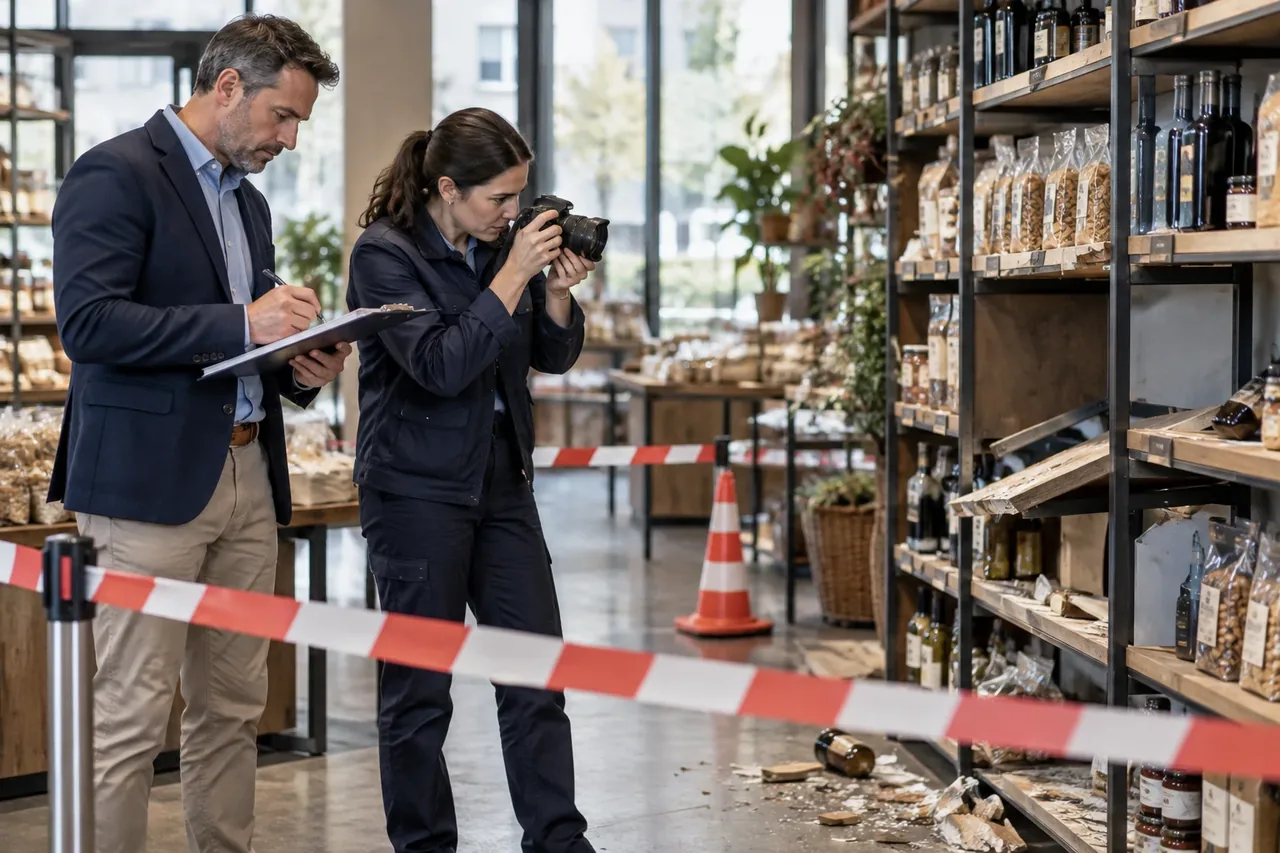
After an incident, the business must protect people, limit further damage and organise evidence. A confused response can make an already difficult situation harder to assess. The insurer should be contacted through the agreed channel while legal responsibility remains subject to proper investigation.
The business question
After an incident, the business must protect people, limit further damage and organise evidence. A confused response can make an already difficult situation harder to assess. The insurer should be contacted through the agreed channel while legal responsibility remains subject to proper investigation.
Understand the mechanism
The policy sets notification and cooperation requirements. These must be read rather than invented from general insurance practice. Defence and compensation are not automatically available for every allegation; the insurer assesses the facts and contractual scope.
Hypothetical business case
A fictional cleaning business is told that a customer’s valuable surface has been damaged. It records the product used, photographs, timing and staff observations, while securing the area. It does not promise an insurance payout or erase records in an attempt to protect its reputation.
Decisions before you commit
Give staff a short incident card: make the situation safe, record facts, preserve documents and contact the designated manager. Notify the insurer promptly as required. Obtain guidance before agreeing settlements or signing admissions, while continuing appropriate customer communication and necessary mitigation.
Your evidence pack
Keep dated photographs, work instructions, customer correspondence, witness details and insurer notifications securely. Use a single factual timeline. After assessment, review whether equipment, training or quality controls should change, without treating the claim decision as a substitute for prevention.
Stress-test the decision
Rehearse the reporting process when no incident is under way. Can a weekend supervisor find the policy number, emergency contact and approved incident form? Decide who handles customer updates and who preserves the original records. Use factual language and separate observations from assumptions about causation. A calm acknowledgement of the complaint is different from a legal admission or a promise that insurance will pay. Where immediate mitigation is necessary, document what was done and why. Follow the insurer’s instructions for cooperation while seeking legal guidance where responsibility is disputed.
Trade-offs and implementation
Keep the original evidence and create a separate working summary. Editing photographs or rewriting staff notes can obscure what was first observed. Preserve messages and material records relevant to the allegation through appropriate secure procedures. The team needs access suitable to its role, not a company-wide broadcast of customer information.
Communicate with the customer at agreed intervals even when the insurer has not reached a decision. State what is known, which steps are being taken and when the next update is expected. Do not invent a coverage result to reassure the client. After the event, examine the practical cause and change training or controls where justified. A rejected insurance claim does not mean no prevention lesson exists, and a paid claim does not prove operations are safe. A structured incident review separates customer care, legal assessment, insurance handling and quality improvement, with an owner for each strand.
Confirm who can approve emergency spending and how it is documented. A safe response needs both operational authority and a record suitable for subsequent assessment.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
- Reference AXA Switzerland: professional liability contract conditions, version January 2025 (example; individual contracts may differ) ↗
- Reference Zurich Switzerland: commercial liability cover and contractual distinctions (product example) ↗
- Reference SECO SME portal: social security schemes and business insurance ↗
- Reference SECO SME portal: insurance according to legal structure ↗
- Press SWI swissinfo: What happens when victims cannot get legal remedy in Swiss courts (2024; long-tail context) ↗
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


