Your commercial lease becomes a dispute: which support is insured?
A practical review of business premises, repair duties, rent disagreements and lease termination, with a hypothetical scenario and a contract comparison framework.
The decision behind the headline
This review focuses on business premises, repair duties, rent disagreements and lease termination.
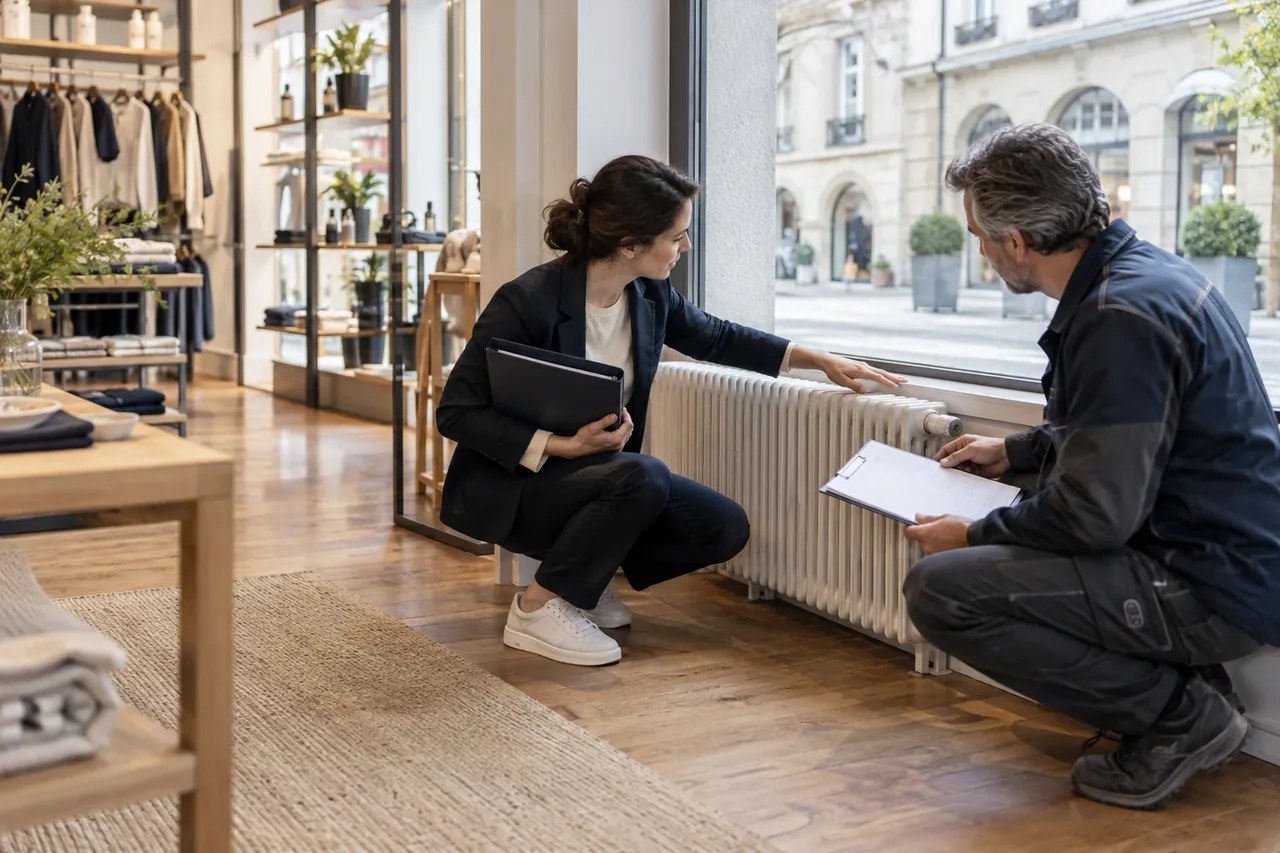
For the heating dispute, first identify the equipment and the repair duty alleged by each party. Gather the lease, inspection record, prior maintenance and the first notice of the problem. A technical report can clarify a failed component, but it does not automatically interpret the lease or decide the legal allocation. Keep any formal notice separate from ordinary maintenance emails because the procedural significance can differ.
A hypothetical scenario to test
A shop and landlord disagree over responsibility for a damaged heating installation. This is an invented example, not a reported claim or a promised payout. Reconstruct the sequence from the first sign of trouble to ordinary service resuming. Ask what would happen if the problem occurred during a holiday or at the busiest time of year. The stress test should expose assumptions about availability and timing before they are relied upon.
Ask the legal insurer whether the named business premises and disputed tenancy fall within cover. If renovation, ownership or construction defects are involved, check those fields explicitly rather than assuming tenant protection includes them. Discuss the competent conciliation authority with counsel using the actual location; the Federal Office for Housing’s information provides a useful starting point. Track the operational consequences, such as cancelled opening hours, separately from the legal expense claim. If a temporary repair is considered, clarify approval and preserve evidence before altering the failed installation where safely possible. The aim is to maintain usable premises and a documented position without letting an uncertain insurance decision obscure a time-sensitive lease procedure.
Identify the contractual boundary
Conciliation is a distinct procedural route, not an informal complaint to the landlord. The Federal Office for Housing provides information and authority contacts. For your premises, establish the competent authority and preserve formal notices; ask a legal professional about deadlines and the applicable commercial-lease procedure.
Compare the wording, then the price
Use an identical scenario with each insurer and request clarification of tenant-law fields, listed premises, excluded construction matters and procedural costs. Ask for the relevant clause and a written explanation of anything left uncertain. An optional extension should appear in the schedule, not merely in a sales discussion.
Reduce the exposure before transfer
A useful first action is to record premises condition and clarify maintenance responsibilities when signing. Assign an owner, a completion date and a simple test of whether the measure works. Written procedures matter only if staff can find and use them under pressure.
Evidence and the next review
Prepare lease, inspection report, repair requests, photographs and official notices. Date the records and keep an accessible copy away from the affected process. Preserve procedural deadlines even while the insurer assesses eligibility. A new policy should not be assumed to cover a dispute already known. Review the arrangement when your activity, technology, locations or counterparties change.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.