
A dropped phone is not a theft claim: map accidental breakage before buying cover
Contents insurance, device cover, liability and warranty answer different questions. Compare the deductible with repair cost before adding another policy.
Start with what actually happened
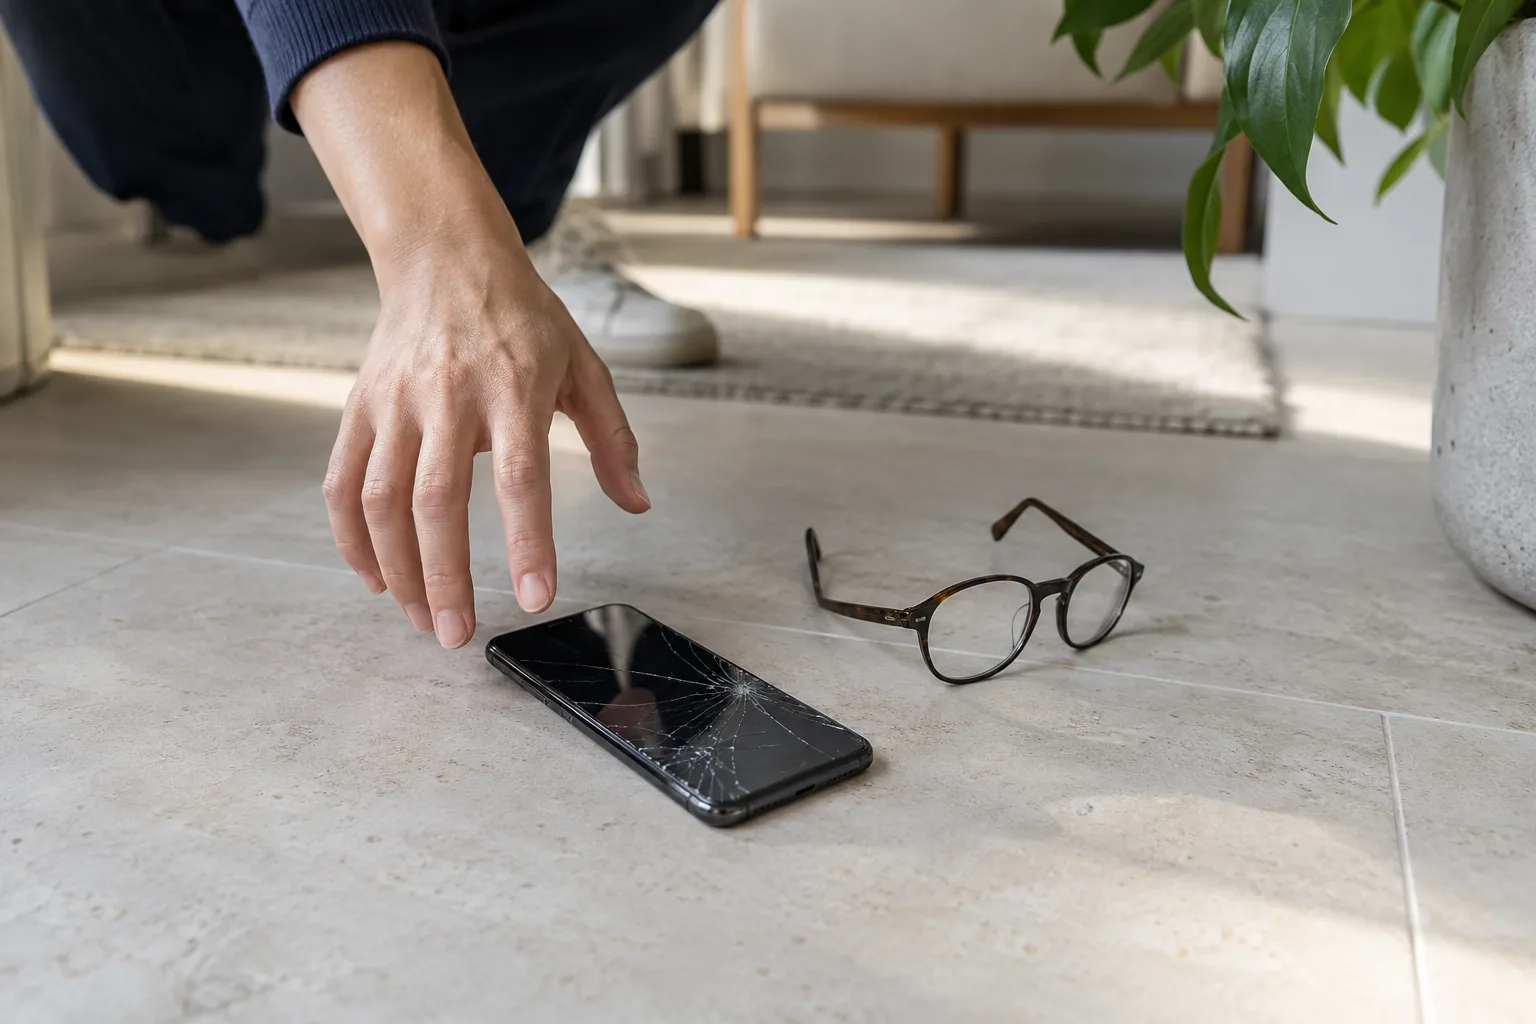
You drop your own smartphone onto a tiled floor and the screen cracks. Nothing has been stolen and nobody else's property has necessarily been damaged. That factual description matters more than the general label home insurance. This dossier, checked on 15 October 2026, looks at accidental damage to personal devices. Basic contents cover, an electronics extension, a retailer plan and private liability should not be assumed to respond in the same way. Record the event honestly. Reclassifying a drop as theft or a manufacturing defect does not improve the claim; it creates an inaccurate account of the loss.
Separate the object from the insured event
An object appearing in your contents inventory does not mean every cause of damage is insured. AXA's Swiss material distinguishes basic events such as fire, water and theft from additional device protection for accidental damage. It also presents separate options for glasses and hearing aids. Those examples illustrate modular cover, not a promise about your own insurer. Check the schedule for the actual object, accidental-damage wording, territory, loss versus breakage, repair conditions and exclusions. A glass-breakage benefit for furniture should not be assumed to cover an electronic screen simply because the screen contains glass.
A hypothetical repair calculation
Imagine an authorised screen repair costs CHF 280 and a relevant policy has a CHF 200 deductible. If the entire repair is otherwise eligible, the potential contribution is CHF 80. Compare that with an invented annual premium of CHF 100: one such repair would not, by itself, recover that year's premium. This is not an actuarial conclusion or a market quotation; other events, replacement costs and your ability to absorb a loss matter. With a CHF 900 eligible repair and the same deductible, the possible contribution changes substantially. Use actual repair options and terms rather than the phone's original purchase price alone.
Warranty and liability follow different routes
A warranty concerns defects and the applicable seller's obligations; it is not automatically insurance against your own accidental drop. The federal consumer bureau's FAQ explains why defect evidence and repair documentation matter. If another person caused the damage, responsibility and their liability cover need examination instead. If you broke your own device, do not assume private liability pays merely because you were careless. Before accepting a retailer replacement plan, compare it with existing household extensions and any manufacturer service arrangement. Two contracts do not mean two payments for the same loss, and overlapping paperwork can make a modest claim unnecessarily confusing.
Decide what to retain yourself
List the expensive portable items in the household, their realistic repair or replacement options and the deductible for each route. Keep purchase proof, serial numbers and secure backups; insurance does not reconstruct unbacked-up memories. After a loss, photograph the damage, protect the device and ask about repair approval before disposal. Remove personal data safely when handing equipment over. A modest emergency repair fund may suit inexpensive devices; broader cover may be useful where one large loss would strain the budget. The useful comparison is between the financial shock retained and the precise protection purchased, not between reassuring product names.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


