
Your shop is intact but customers cannot enter: check the interruption trigger
Lost sales alone do not establish a property-insurance claim. Identify the cause, any material damage and the exact extension before budgeting reimbursement.
Interruption and insured interruption are different
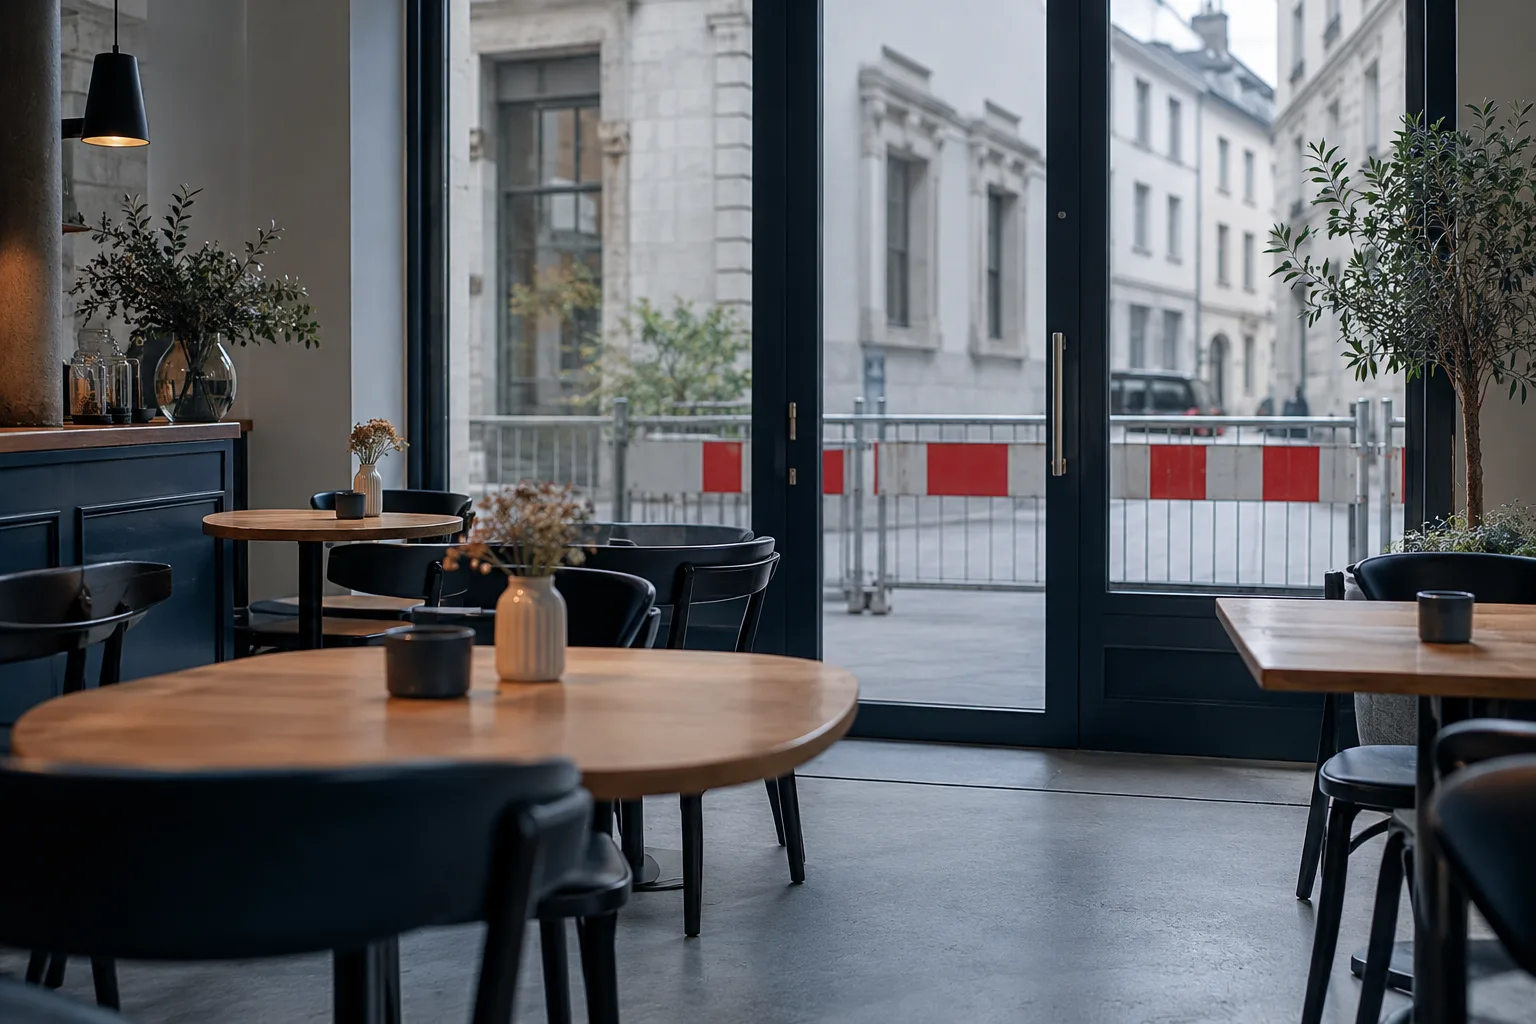
A cafe has power, stock and undamaged furniture, yet customers cannot reach the entrance because the street is closed. The loss is real. Whether it falls within a property policy is a separate question. Checked on 15 October 2026, this dossier focuses on access restrictions without damage to the business's own premises. Do not begin by multiplying lost sales and expecting the insurer to pay. Begin with the event that caused the restriction, who imposed it, where it occurred and which contractual trigger might apply. A general business-interruption label does not settle those facts.
Read the causal link before the indemnity period
AXA's Swiss property information describes interruption losses resulting from an insured material-damage event. Other clauses or extensions must be checked separately; do not infer them from the base product description. Ask about damage near the premises, denial of access, authority orders, distance limits, duration, waiting periods and exclusions. A roadworks closure, an unsafe neighbouring building and a health-related closure need not have the same outcome. The insurer's separate infection product illustrates how a non-standard trigger can have a defined list of causes and exclusions. Its existence does not mean every closure by an authority is insured.
A hypothetical six-day closure
Imagine a cafe normally makes CHF 2,000 of sales a day. A six-day access restriction suggests CHF 12,000 of missed turnover, but some food purchases and other variable costs may be avoided, while selected fixed costs continue. If CHF 4,000 of costs are saved, the simple remaining economic gap would be CHF 8,000 before extra mitigation costs. These are invented planning figures, not the policy's indemnity formula. Actual lost demand, alternative sales, limits and deductibles matter, and no payment follows unless the trigger is covered. Keeping economic loss separate from insured loss prevents an optimistic reimbursement assumption from hiding a cash shortage.
Preserve evidence and consider workable alternatives
Keep the written restriction, photographs of access, relevant dates, booking cancellations, normal sales comparisons and the costs saved. Ask the authority or landlord about expected duration without treating an informal estimate as certain. Discuss proportionate alternatives such as collection elsewhere, delivery or temporary premises with the insurer before committing to significant costs. A workaround can preserve customers but may be uneconomic for a short closure. Respect safety instructions; do not redirect customers through a prohibited route to protect turnover. The linked Le Temps article from 2020 gives historical context on causation disputes, not current contractual wording or a precedent deciding this scenario.
Turn the uncertainty into a continuity decision
Request a written coverage position identifying the clause and any missing evidence. If access loss is outside cover, record the retained exposure and decide whether future extensions are available and worthwhile. A reserve, alternative sales channel and clear customer communication can still reduce vulnerability, but their costs must be realistic. Review the need at renewal using the business's actual location and dependence on walk-in trade. Do not buy a broad-sounding extension without testing a concrete closure example. The aim is to know which interruption can be financed by insurance and which needs an operational plan, before the next barrier appears.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


