
Your goods on the road: property cover does not automatically follow the van
Map loading, transit and unloading before comparing transport protection. Insuring your goods is different from insuring a carrier’s liability.
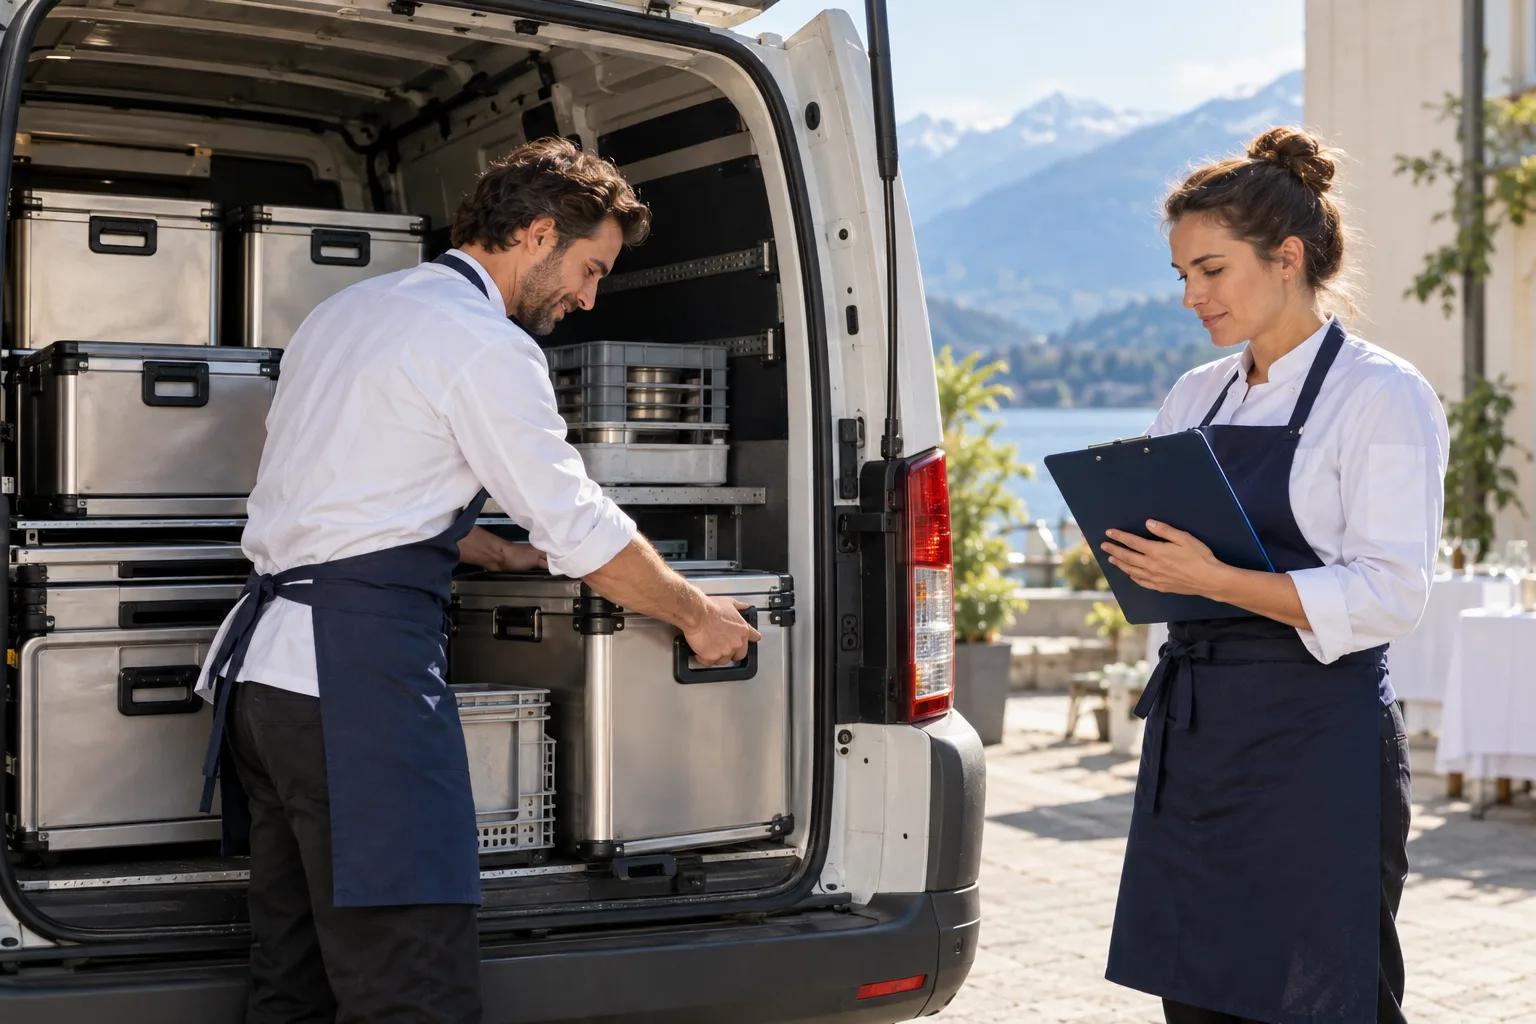
A new location can mean a new risk
A catering business may have excellent cover for its kitchen while equipment and stock spend hours in a van. The relevant question is not whether the business has property insurance, but whether the actual journey, cargo and event fall within the agreed scope. The source review on 14 October 2026 distinguishes insurance of goods from transport liability using Swiss obligations law and provider information. Neither your motor policy nor a carrier's liability policy automatically promises full replacement of your cargo. Start with what you own, what you have borrowed and whose responsibility applies at each step of the delivery.
Map loading, transit and temporary storage
List regular routes, maximum cargo values, own vehicles, hired vehicles and third-party carriers. Include loading and unloading, overnight stops, temporary event storage and the return journey. Ask which stages and territories are covered, how theft from an unattended vehicle is treated, and whether packing or securing requirements apply. Temperature-sensitive stock and fragile equipment need specific questions; a broad goods description can conceal important exclusions. Distinguish value per trip from annual turnover. A business with modest yearly sales can still carry a concentrated valuable load on one busy weekend, making a simple turnover-based discussion inadequate for that exposure.
A hypothetical event delivery
Imagine a caterer carries CHF 12,000 of owned equipment and CHF 3,000 of stock. An accident damages CHF 4,000 of equipment and CHF 1,000 of stock. The potential material loss is CHF 5,000, before valuation, salvage and deductible questions. If a covered settlement of that amount had a hypothetical CHF 500 deductible, the net payment would be CHF 4,500. But the event cancellation and lost margin are not automatically added to the same claim. Nor is a hired carrier necessarily liable for every franc of replacement cost. The figures illustrate separate exposures, not promised benefits. Keep inventories and purchase records for the real journey.
Transfer risk without ignoring the retained part
Using a professional carrier can improve handling, but the carrier's responsibility and compensation terms must be understood. Covering the cargo directly can avoid relying solely on proving someone else's liability, subject to the goods policy. Higher limits may be worthwhile for occasional peaks; better packing and avoiding unattended overnight storage can reduce exposure without buying every possible extension. Compare premium, deductible, excluded events and practical obligations together. Do not assume contractual penalties or lost business are covered because the damaged object is covered. Press guidance on international moving illustrates why transport compensation deserves scrutiny, without establishing commercial-policy terms for your business.
Make each trip auditable
Before departure, create a manifest with ownership, approximate value, destination and condition; verify secure loading and who accepts the goods. Photograph the load proportionately without exposing confidential client information. At delivery, record damage or shortages and preserve packaging and evidence, then notify the insurer or carrier promptly according to the applicable instructions. Avoid disposing of damaged goods before inspection is addressed. Reconcile reimbursement and retained losses afterwards. Review protection when new products, higher peak loads or cross-border routes are introduced. This routine gives a transport claim a clear factual foundation and makes uninsured gaps visible before the next journey.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


