
Customer property in your care: map custody, work damage and theft separately
A repair shop or service business can hold valuable belongings without having identical cover for every type of damage. Test the exact activity and property.
Possession changes the insurance question
A customer's watch, laptop or instrument in your workshop is not simply another third-party object across the street. You may be storing it, transporting it or working directly on it, and the policy can distinguish those exposures. The review on 14 October 2026 uses Swiss obligations law and current business-liability material, including policy conditions. Do not infer cover for entrusted property from the general statement that third-party material damage is insured. Give the insurer the actual workflow. The item being repaired, damage to other property and the cost of correcting your own defective service may fall into different categories.
Follow the object through the business
Create a custody map from receipt to return: who signs it in, where it is stored, what work is performed, whether subcontractors receive it and how transport is arranged. Record ownership and condition without unnecessary customer data. Ask specifically about damage during processing, property under your control, theft, disappearance and items outside the premises. Identify the limit per item, per event and across the year where applicable. A valuable-object concentration can make a modest single-item limit misleading. Written activity descriptions and endorsements should match actual operations rather than a historic business label that no longer reflects what staff do.
A hypothetical watch with three cost categories
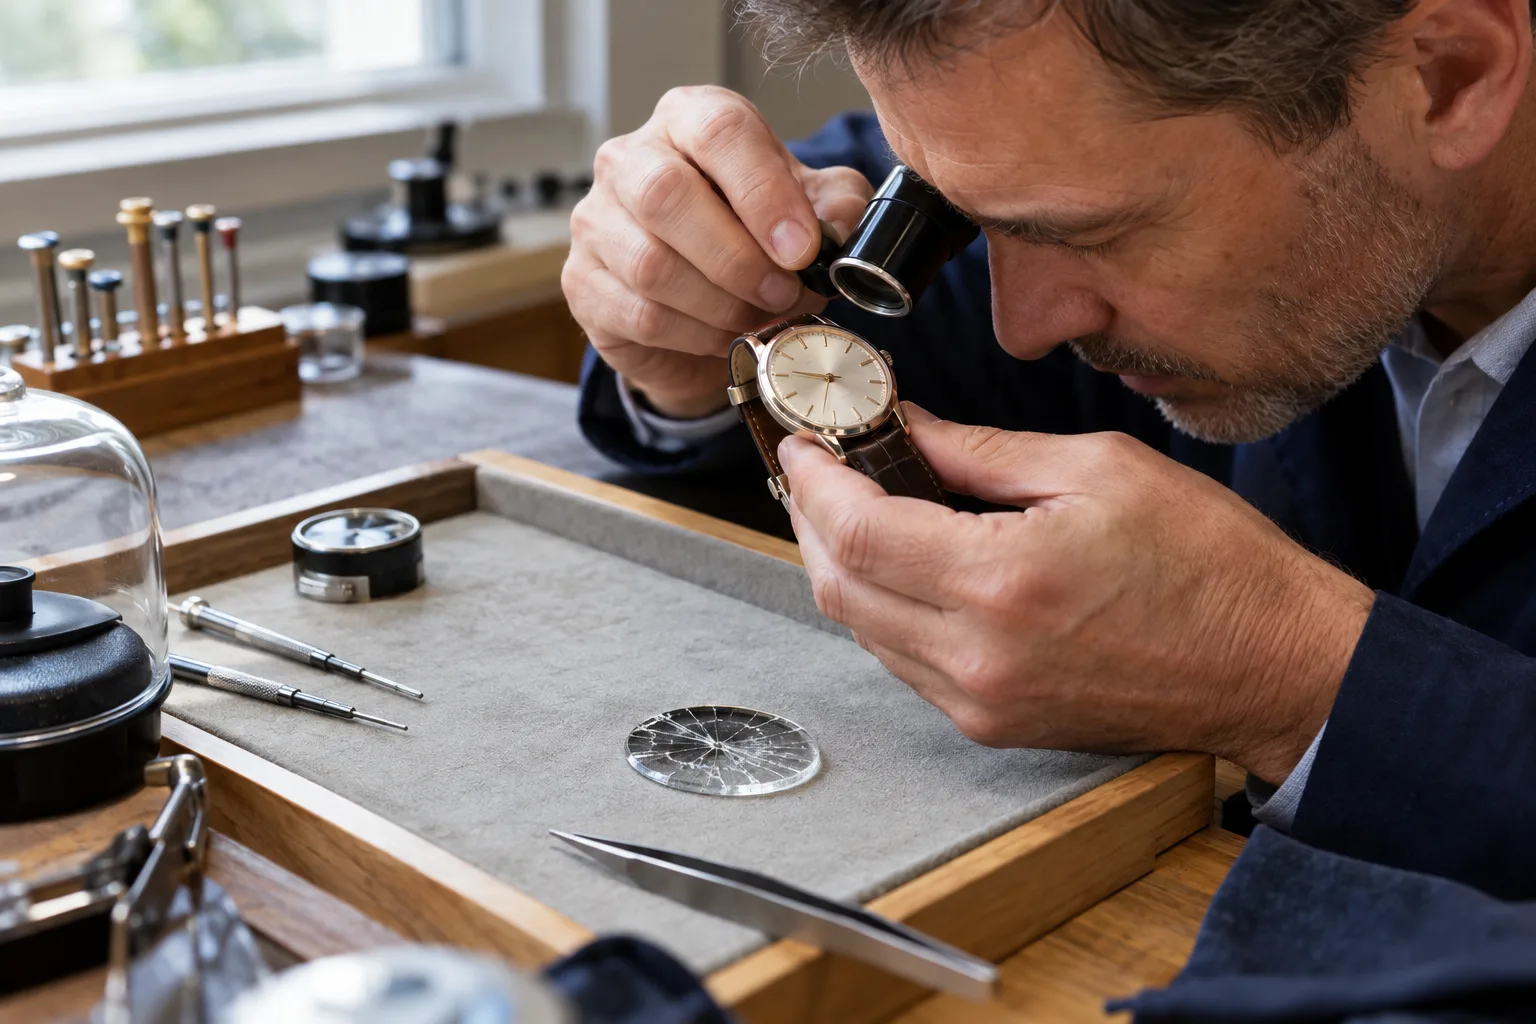
Imagine a customer leaves a watch valued at CHF 8,000. During a service, an employee damages its crystal; the proposed repair is CHF 900. Separately, the original service costs CHF 200 and the customer claims CHF 500 for a missed appointment. These are three different questions, not an automatically insured CHF 1,600 bill. Responsibility, causation and policy exclusions must be assessed, including whether redoing your own work is covered. The example is not a product quote. Provide photographs, intake condition, work records and an independent repair estimate where appropriate. Preserve the parts and do not promise a replacement watch before the insurer has considered the claim.
Limits and operating controls complement each other
Buying a higher overall liability limit does not remove a custody exclusion or improve a weak handover process. A targeted extension may be more useful, but its scope and deductible need to fit the real exposure. Prevention also has a cost: secure storage, two-person inventory checks for valuable items and controlled subcontractor handovers take staff time. Compare that effort with the possible uninsured loss and customer dispute. Do not ask customers to accept sweeping liability waivers without qualified advice. A form cannot reliably replace lawful care or turn an uninsurable promise into cover. Keep commercial agreements and insurance assumptions aligned.
Review before the next valuable delivery
Send the insurer a concrete example of the most valuable item normally held and the maximum value held together. Request answers for storage, work, transit and outsourced steps. Update the policy description when new services or categories are added. At intake, document condition, agreed work and return process; after an incident, secure the item and preserve the evidence, then report promptly. Keep the customer informed without making unsupported statements about payment. The useful result is a clear responsibility-and-cover map, backed by operating records. It does not guarantee that every entrusted item or every contractual compensation demand will be insured.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
- Reference Fedlex — Code des obligations ↗
- Reference AXA — Responsabilité civile d’entreprise ↗
- Reference AXA — CGA responsabilité civile entreprises ↗
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


