
Minor accident, later complication: report the event while the facts are fresh
A short absence can still require an accident report; early factual documentation protects the employee, employer and insurer if symptoms later worsen.
Small at first does not mean irrelevant
Suva distinguishes a minor accident from an ordinary accident using the duration of incapacity: its current guidance describes minor cases as no incapacity or no more than three calendar days, including the accident day plus two. Accidents and occupational diseases should still be reported as quickly as possible. A bruise may resolve, but a wrist, dental or back problem can develop after the first shift. An early report does not guarantee acceptance; it preserves a contemporaneous account for the insurer’s legal and medical assessment.
Capture facts without diagnosing
Record date, exact time, place, task, movement, object, witnesses, immediate symptoms, first aid and whether work stopped. Preserve photos or equipment data where lawful, but do not delay treatment. The supervisor should describe what was reported, not speculate about fault or write a medical conclusion. Give the employee the claim reference and tell later doctors that the consultation relates to the accident. Correct errors promptly. Consistent payroll and absence dates matter because the reporting category can change when incapacity lasts longer than first expected.
A hypothetical workshop twist
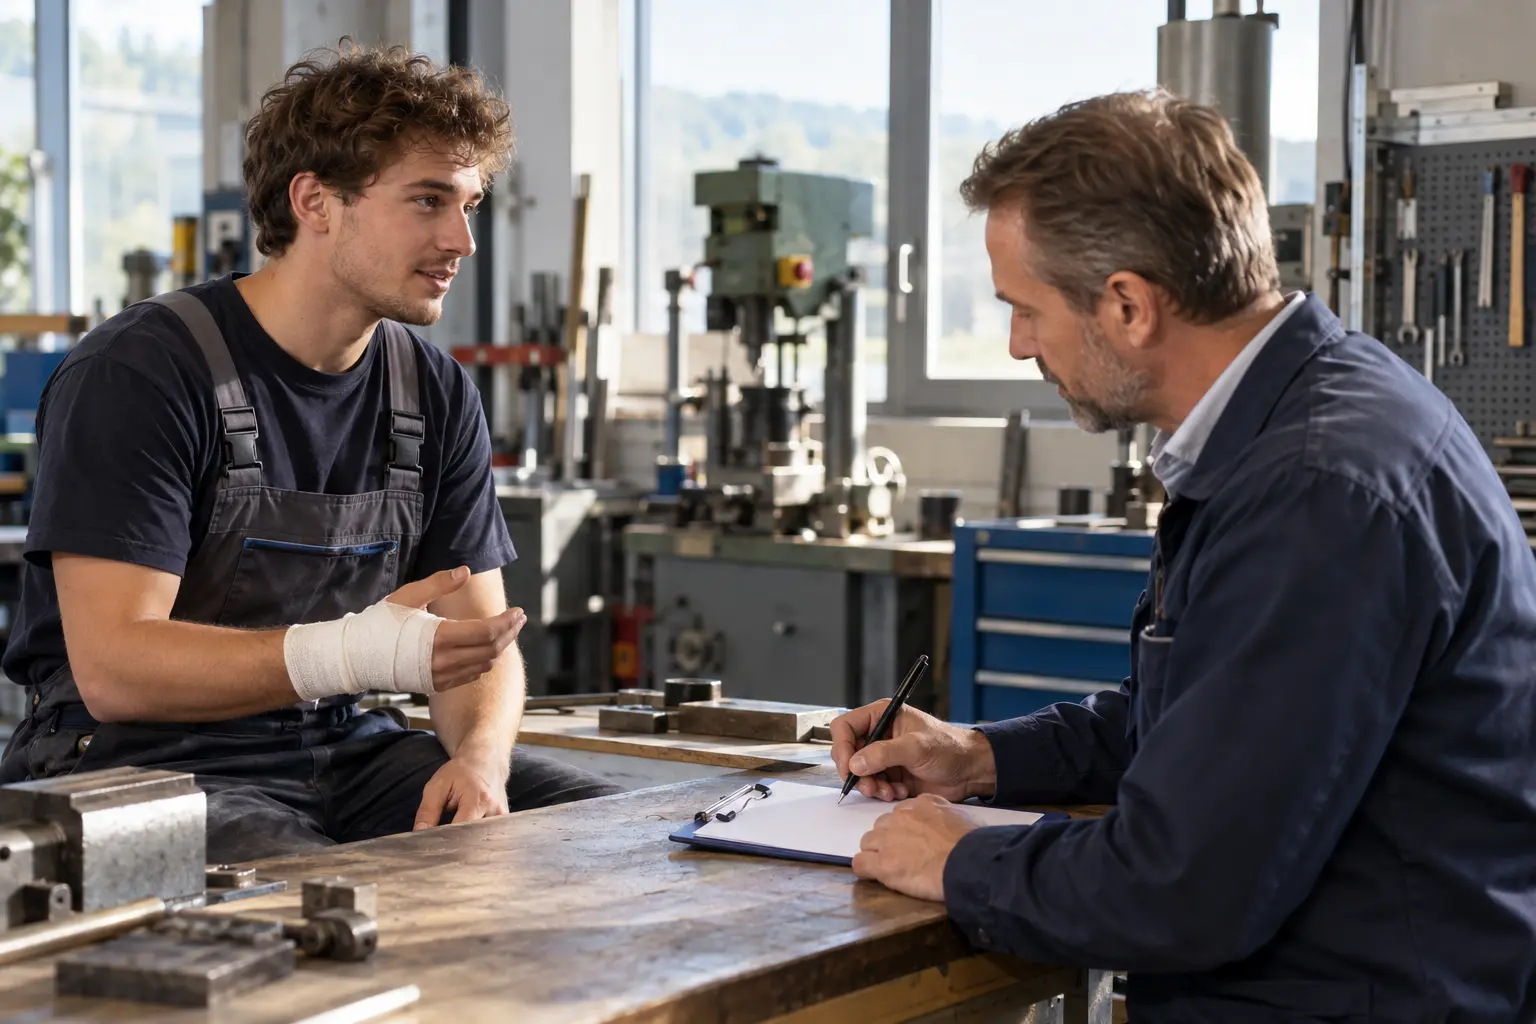
Leo twists his wrist while moving a light component. He finishes the day and expects no absence, so the employer records and submits the event as a minor accident. Two days later swelling increases and a doctor certifies a longer incapacity. HR updates the insurer with the certificate and corrected absence data rather than creating a second event. The insurer assesses whether the legal accident definition and medical link are met. The example does not promise coverage; it shows why the first chronology and later update belong to one file.
Reporting has costs, silence has larger risks
Prompt reports add administration and can tempt teams to treat every discomfort as a formal claim. Under-reporting looks efficient until a delayed complication lacks evidence, undermines trust or produces payroll corrections. A safety investigation should learn from the event without prejudging insurance liability. Employee privacy limits who needs medical detail. Employers should separate prevention records, HR absence management and insurer submissions while keeping dates aligned. The aim is neither maximum claims nor minimum claims, but accurate classification and timely information.
Create a one-page accident routine
Train staff to seek care, secure the area and inform a named contact immediately. Use a form that captures factual chronology, witnesses and work schedule. Assign HR responsibility for the insurer submission, claim number and updates when incapacity crosses the minor-case threshold. Reconcile medical certificates, payroll and return-to-work dates. Review the cause with prevention staff and implement proportionate action. Keep employees informed about which insurer handles the case. A simple routine prevents a small event from becoming a dispute about whether anything was ever reported.
For remote or travelling staff, the routine must work outside the usual premises. Give them the reporting channel, emergency numbers and method for locating the incident before departure. When work and private time are close together, record the schedule and business purpose without forcing the employee to argue the legal category while injured.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


