
Renovating business premises: separate existing property from the works
Ordinary property insurance may not answer every construction risk; define responsibility for stock, fit-out, works, tools and interruption before the first contractor arrives.
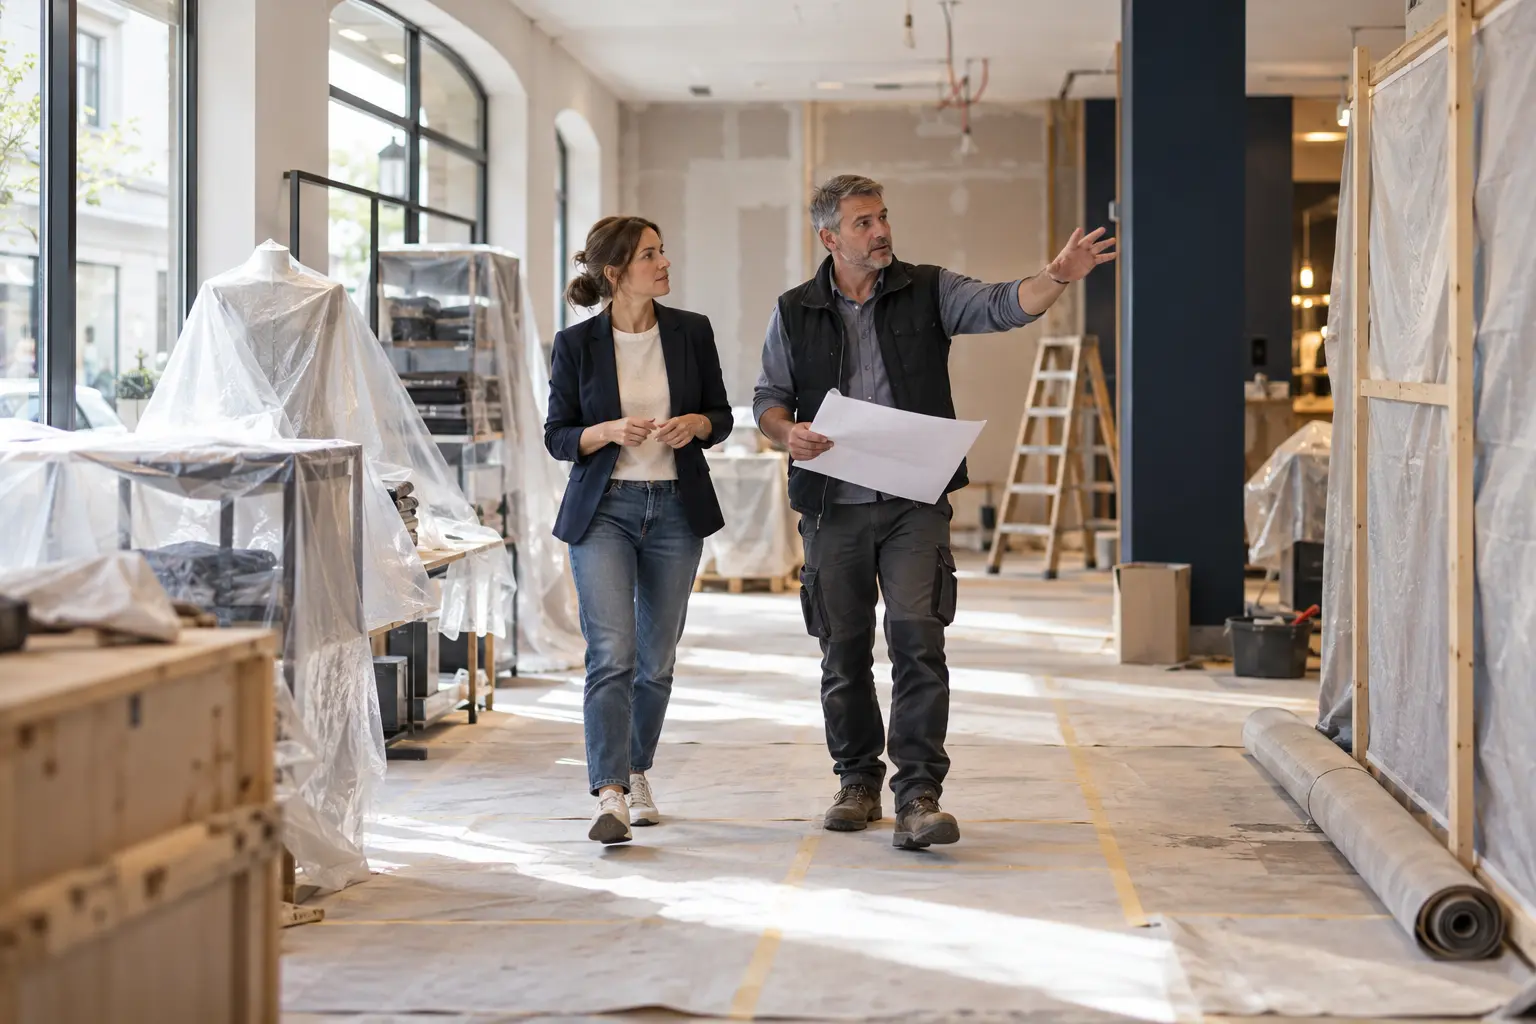
A renovation creates a temporary business you did not insure yesterday
Open walls, hot work, temporary wiring, dust, water shut-offs and contractor access change both the probability and size of loss. Existing contents cover may protect owned furniture and stock under stated perils, while construction work, newly installed fixtures, contractors’ tools and defective workmanship can sit elsewhere. Business interruption may require insured physical damage and a defined indemnity period. Before work starts, tell the property insurer what changes, when and who remains trading. Silence can leave the policy describing a premises that no longer exists operationally.
Draw a responsibility map room by room
List the landlord’s building, tenant improvements, existing contents, delivered materials, works completed, leased equipment and each contractor’s property. Match every category to owner, contract responsibility, insurer, value and dates. Ask about fire prevention, water isolation, security, storage outside, testing and commissioning. Obtain liability evidence from contractors but remember that a certificate is not a guarantee of recovery. Clarify waivers, deductibles and recourse in the works contract. Update sums insured for the finished fit-out before handover, not at the next annual renewal.
A hypothetical boutique refit
A Lausanne boutique closes half its floor for six weeks while a contractor installs fixed counters and lighting. The owner moves premium stock to a locked room and records it, the landlord confirms building responsibilities, and the contractor identifies works and tools cover. The property insurer approves precautions and notes partial trading. A water leak damages stored stock and unfinished joinery; the parties can allocate each item using the pre-work schedule. The example does not prove which policy pays—the contracts, cause and ownership still control.
Staying open trades revenue for exposure
Partial trading preserves customers but increases public access, dust contamination and complexity if an incident stops both old and new areas. Full closure simplifies safety while increasing interruption from day one. The cheapest contractor may carry narrow limits; demanding excessive insurance can exclude skilled small firms. Broad construction cover adds premium but may avoid arguments between ordinary property and contractor liability. Choose based on maximum credible loss, dependency on reopening date and evidence quality—not on a belief that somebody else’s policy will certainly respond.
Hold a pre-start insurance meeting
Provide plans, budget, timetable, contractor list, fire or water work and operating arrangements to landlord, broker and insurer. Photograph and inventory the existing premises. Record permits, hot-work controls, isolation points, alarms, keys and emergency contacts. Require incident notification before repair or disposal, while allowing urgent mitigation. Review values when materials arrive and again at practical completion. Archive commissioning and handover documents. This small governance meeting converts an overlapping construction site into defined property interests and gives interruption planning a realistic reopening clock.
If customers’ goods or consigned stock remain onsite, list them separately from property owned by the business. Contractual responsibility and policy treatment may differ, and the owner may need evidence immediately after a loss. Agree identification, valuation and notification methods with the customer or consignor before dust, fire or water affects the records.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


