
A visitor falls on your premises: preserve the scene before debating fault
Premises incidents can involve legal liability, accident benefits, property management and evidence; a humane response and a disciplined file should happen together.
An injury does not decide liability automatically
When a client, supplier or passer-by falls in business premises, immediate care comes first. Legal liability is a separate question involving the condition of the premises, duty of care, causation, damage and possibly the conduct of several parties. The injured person may also have accident or health insurance. Business liability insurance examines covered legal responsibility and can defend against unfounded demands; it is not a general goodwill fund. Avoid both an instant admission and a cold refusal. Secure the hazard, help the person and preserve objective facts.
Freeze a perishable scene
Record time, weather or cleaning conditions, lighting, floor, furniture, warning signs, footwear observations and witnesses without invading privacy. Preserve CCTV lawfully before automatic deletion and retain maintenance, inspection and cleaning logs. Photograph the area from several neutral angles after urgent care. Identify whether the landlord, contractor, caterer or another tenant controls the surface or object. Notify the insurer promptly and forward correspondence unanswered where the policy requests it. A reconstructed scene weeks later is weaker than a factual file made in minutes.
A hypothetical café fall
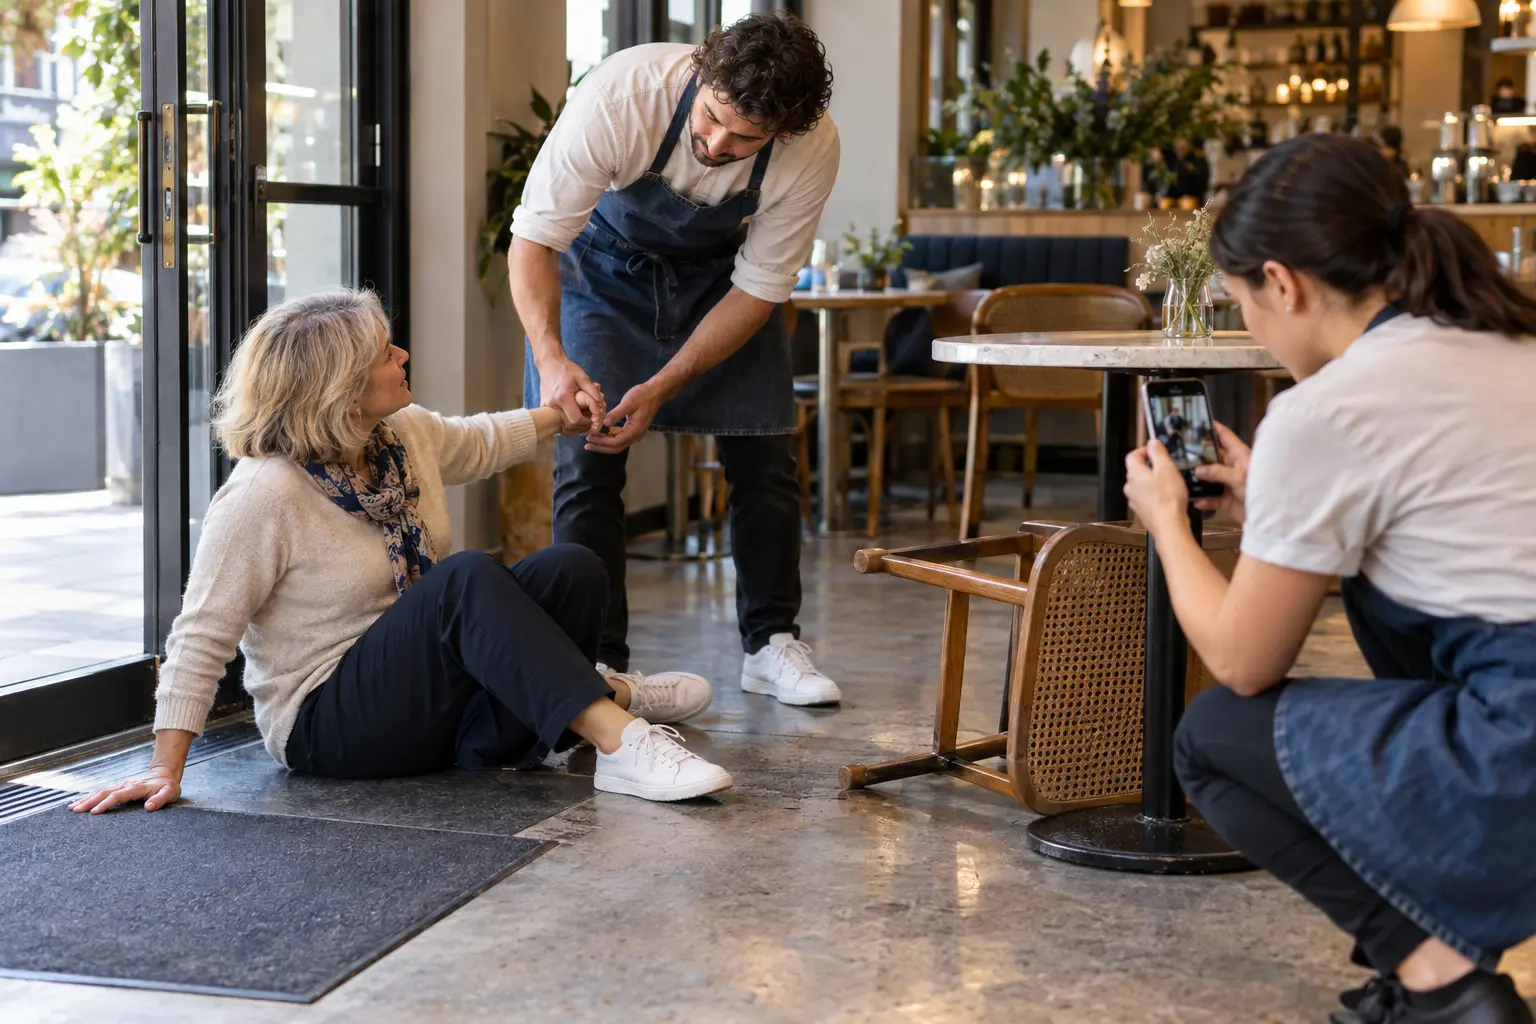
A customer falls when a chair leg fails near a café entrance. Staff call for medical help, isolate the chair, photograph its break and save the purchase and inspection records. They do not tell the customer the business will pay every cost. The café notifies its liability insurer and landlord; the insurer examines whether the chair defect, maintenance and injury are causally linked. A phone image from another customer is requested with consent. The example does not establish liability—it demonstrates care, evidence and coordinated notice.
Customer care and legal discipline are compatible
Paying a taxi or offering practical help can be compassionate, but unclear promises about medical costs may complicate later assessment. Closing the area protects others while interrupting trade. Quick repair restores operations but can destroy evidence unless the component is retained. A large insurance limit provides capacity, not automatic payment; deductibles, territory, activity description and exclusions matter. If another party supplied the defective item, recovery may be possible. The best response protects the person, future visitors and the integrity of every party’s rights.
Practise the first thirty minutes
Give staff an incident card: call emergency services when needed, prevent further harm, appoint one respectful contact, document facts and notify management. Keep inspection schedules and contractor responsibilities accessible. Define who contacts the insurer and who speaks externally. Preserve failed objects and digital recordings securely. After the incident, correct the hazard without altering the evidence trail and review similar locations. Do not post footage or blame the visitor. A rehearsed process reduces both human harm and the uncertainty that drives expensive liability disputes.
Where children, older visitors or people with reduced mobility are frequent, include their foreseeable use in inspections and evacuation planning without assuming individual fault. Review entrance mats, handrails, lighting and temporary displays after every layout change. A risk-sensitive environment supports prevention and provides stronger evidence than a checklist completed only after somebody falls.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


