
After a windstorm: separate home contents, building damage and liability
A damaged terrace can involve several owners and policies; documenting what moved, broke and harmed a neighbour is more useful than guessing one insurer.
The terrace is an insurance boundary
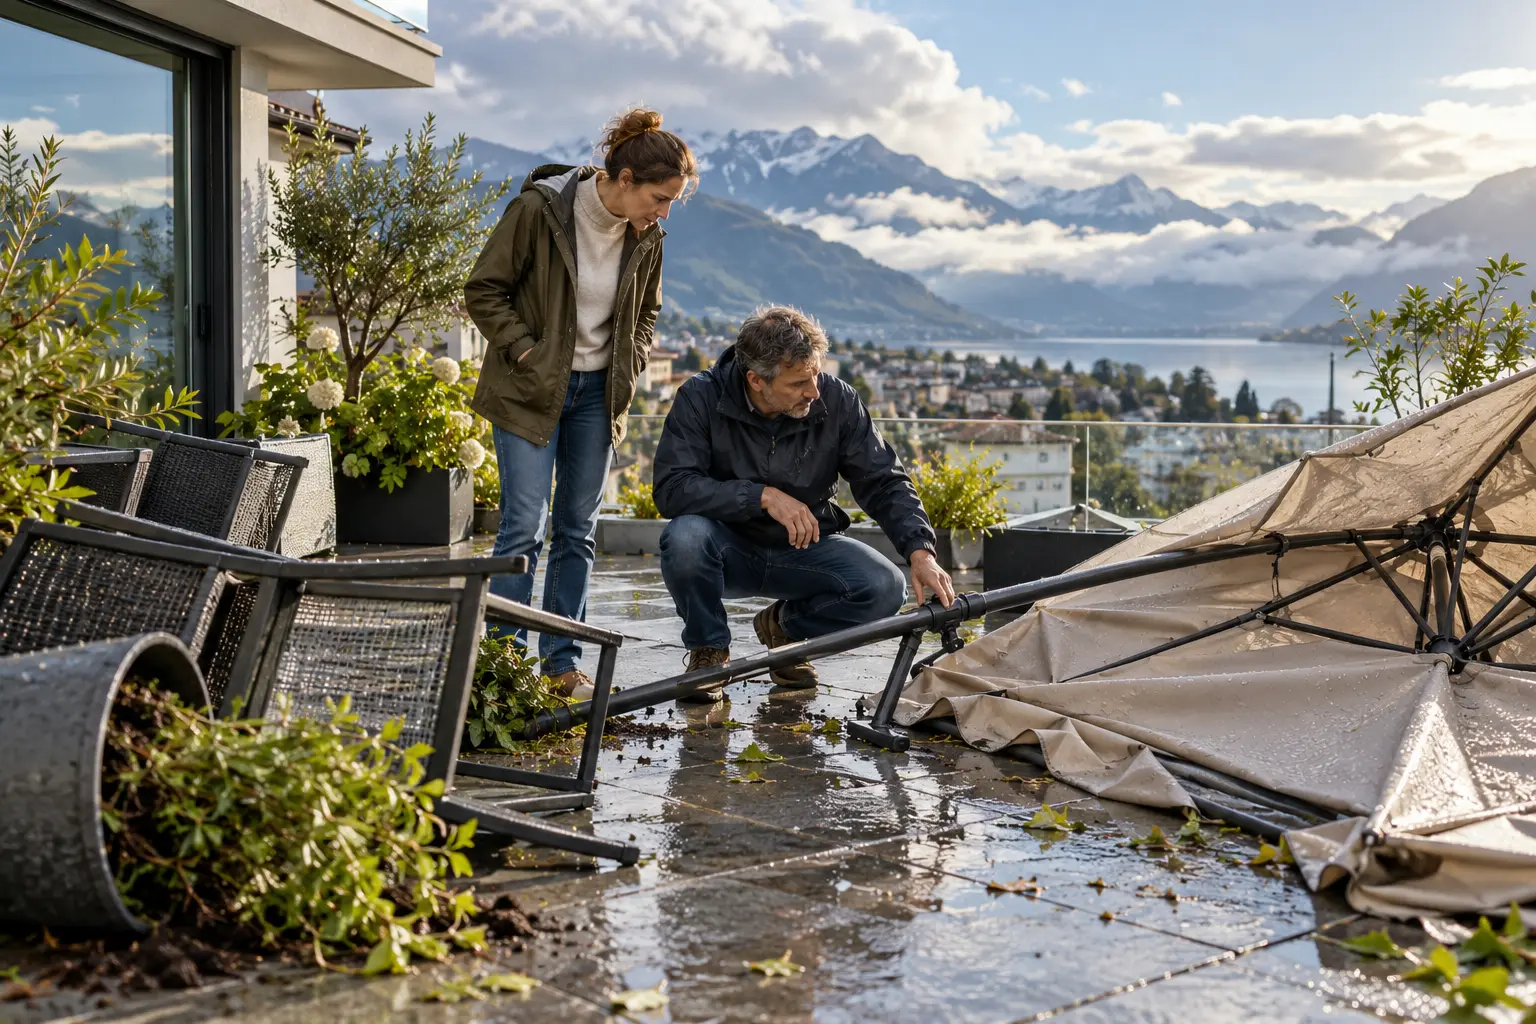
After strong wind, a parasol may be torn, a fixed awning damaged, a planter blown onto a neighbour’s car and water pushed through a door. These items do not all belong to the same cover. Movable household belongings may fall under contents insurance when the peril and item are insured; permanent building elements may belong to the owner or cantonal building insurance; damage caused to a third party may raise private liability. A tenant, condominium owner and landlord therefore start from different ownership maps. Calling the event “storm damage” does not by itself establish coverage or responsibility.
Secure first, photograph before clearing
Keep people away from unstable glass, furniture and awnings. Take wide and close photographs showing the position, anchoring, impact path and neighbouring damage before moving items, unless immediate mitigation is necessary. Record the time, weather alerts and witness details without exaggerating wind speed. Keep broken parts and receipts where safe. Notify the landlord or condominium administrator promptly when building components are involved. If a third party claims damage, acknowledge receipt without admitting liability and forward the demand to the liability insurer. Emergency action should limit further loss, not erase evidence.
A hypothetical planter incident
During a night storm, a heavy planter on Amira’s rented terrace tips over, cracks two tiles and sends soil and a metal support onto a neighbour’s parked scooter. Amira photographs the anchoring and debris, moves the remaining planters indoors and informs the property manager and insurer. The building side assesses the tiles, contents cover considers her movable furniture, and private liability examines the scooter claim and whether she bears legal responsibility. The policies may apply different deductibles, peril definitions and exclusions. The example does not assume negligence merely because the object came from her terrace.
Better protection may mean better anchoring
Including simple natural hazards in contents cover can be valuable, but policy wording may set event thresholds, item limits or duties to protect outdoor property. A low deductible helps smaller losses but raises premium. Storing furniture before a warning costs time and preserves property; permanently fixing objects may shift them toward the building and require landlord approval. Liability cover protects against justified third-party claims and disputes unjustified ones, but it does not replace maintenance. A balcony with repeated wind exposure should be managed as a physical risk even when insurance is broad.
Create a seasonal terrace record
Photograph furniture, awnings, planters, bicycles and their anchors before winter, retaining purchase evidence for valuable items. Ask who owns and insures fixed additions and obtain permission for installations. Read the natural-hazard definition, outdoor-property limits and deductibles in contents and building policies. Keep insurer and property-manager contacts offline. After a storm, mitigate, document, separate each damaged item by owner and send consistent facts to the relevant parties. Do not seek two payments for one loss. Insurance can allocate defined financial damage, but orderly evidence and prevention decide how quickly the overlapping questions can be resolved.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
- Reference Fedlex — Code des obligations ↗
- Reference FINMA — Autorisation des assurances dommages ↗
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


