
Occupational disease is not simply an accident that develops slowly
Recognition depends on the work exposure and medical evidence; prevention must address concentration and duration before symptoms become disabling.
The legal route starts with causation
An accident is generally a sudden, unintended damaging event meeting the statutory definition. An occupational disease develops through work exposure and is recognised under separate LAA criteria. The label cannot be chosen merely because one route appears more generous. Allergic asthma from flour dust, hearing loss from noise or skin disease from substances require a medical and occupational history that links exposure to work. Suva explains that concentration, hazard characteristics and duration matter. The employer should report a suspected occupational disease and support fact-finding rather than wait for certainty or treat symptoms as a private health issue.
Document the workplace, not only the diagnosis
Record tasks, products, exposure frequency, ventilation, protective equipment, cleaning methods and changes over time. Preserve safety data sheets and maintenance logs. Encourage early medical assessment and give the clinician an accurate job description. Compare symptoms on workdays, weekends and holidays without coaching an answer. Report through the responsible accident insurer and cooperate with requested occupational-medicine evaluation. Privacy still applies: managers need functional restrictions and preventive actions, not unrestricted medical details. A rejected occupational-disease classification does not mean the illness is unreal; it means another insurance and employment pathway may apply.
A hypothetical bakery case
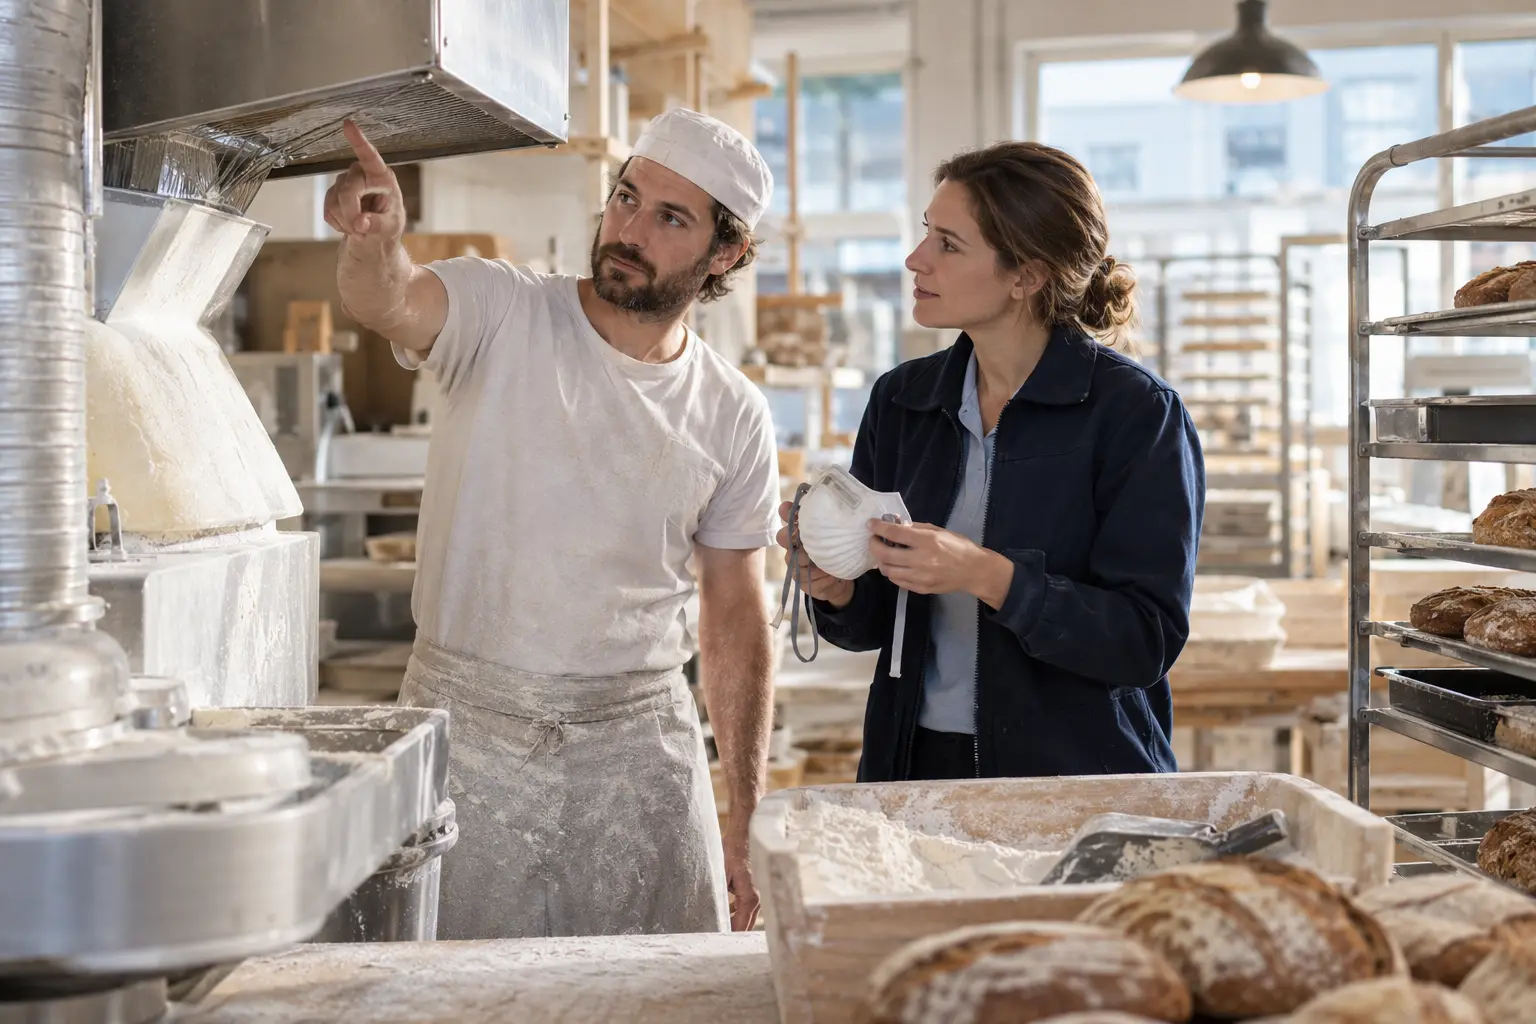
Marek has worked in a bakery for six years and develops wheezing during mixing shifts. The employer documents flour-handling tasks, extraction maintenance and mask availability, then reports a suspected occupational disease. Medical specialists assess allergy and exposure rather than calling one episode an accident. The bakery changes pouring methods, improves local extraction and temporarily reallocates tasks. The insurer decides recognition on the evidence; the company does not promise an outcome. Even if symptoms improve, the controls remain because colleagues share the exposure. The example shows why prevention and insurance assessment should proceed together.
Prevention choices have operational costs
Enclosed transfer, extraction and low-dust techniques cost more than disposable masks but control the hazard at source. Personal protection is useful when correctly selected and worn, yet it relies on behaviour and fit. Reassigning a worker can protect health while affecting skills, income and staffing. Waiting for a confirmed claim avoids premature expense but can permit irreversible harm and more absences. Premium considerations are secondary to the legal duty of protection. The sound programme uses technical, organisational and personal measures in that order and measures whether exposure actually falls.
Create an exposure-review routine
Identify substances and tasks capable of causing chronic disease, assign owners and schedule ventilation or extraction checks. Train staff to report early symptoms without fear and give them a clear reporting channel. When a case arises, preserve exposure records, notify the insurer, coordinate occupational medicine and document interim restrictions. Review colleagues performing the same work. After changes, verify performance rather than relying on purchase invoices. Accident insurance can provide statutory benefits when criteria are met; accurate exposure evidence supports the decision, while primary prevention remains the most reliable way to protect employees.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


