
Maternity leave when self-employed: protect both income and the business
The statutory allowance replaces part of personal earnings for a defined period; it does not automatically fund rent, payroll or a substitute.
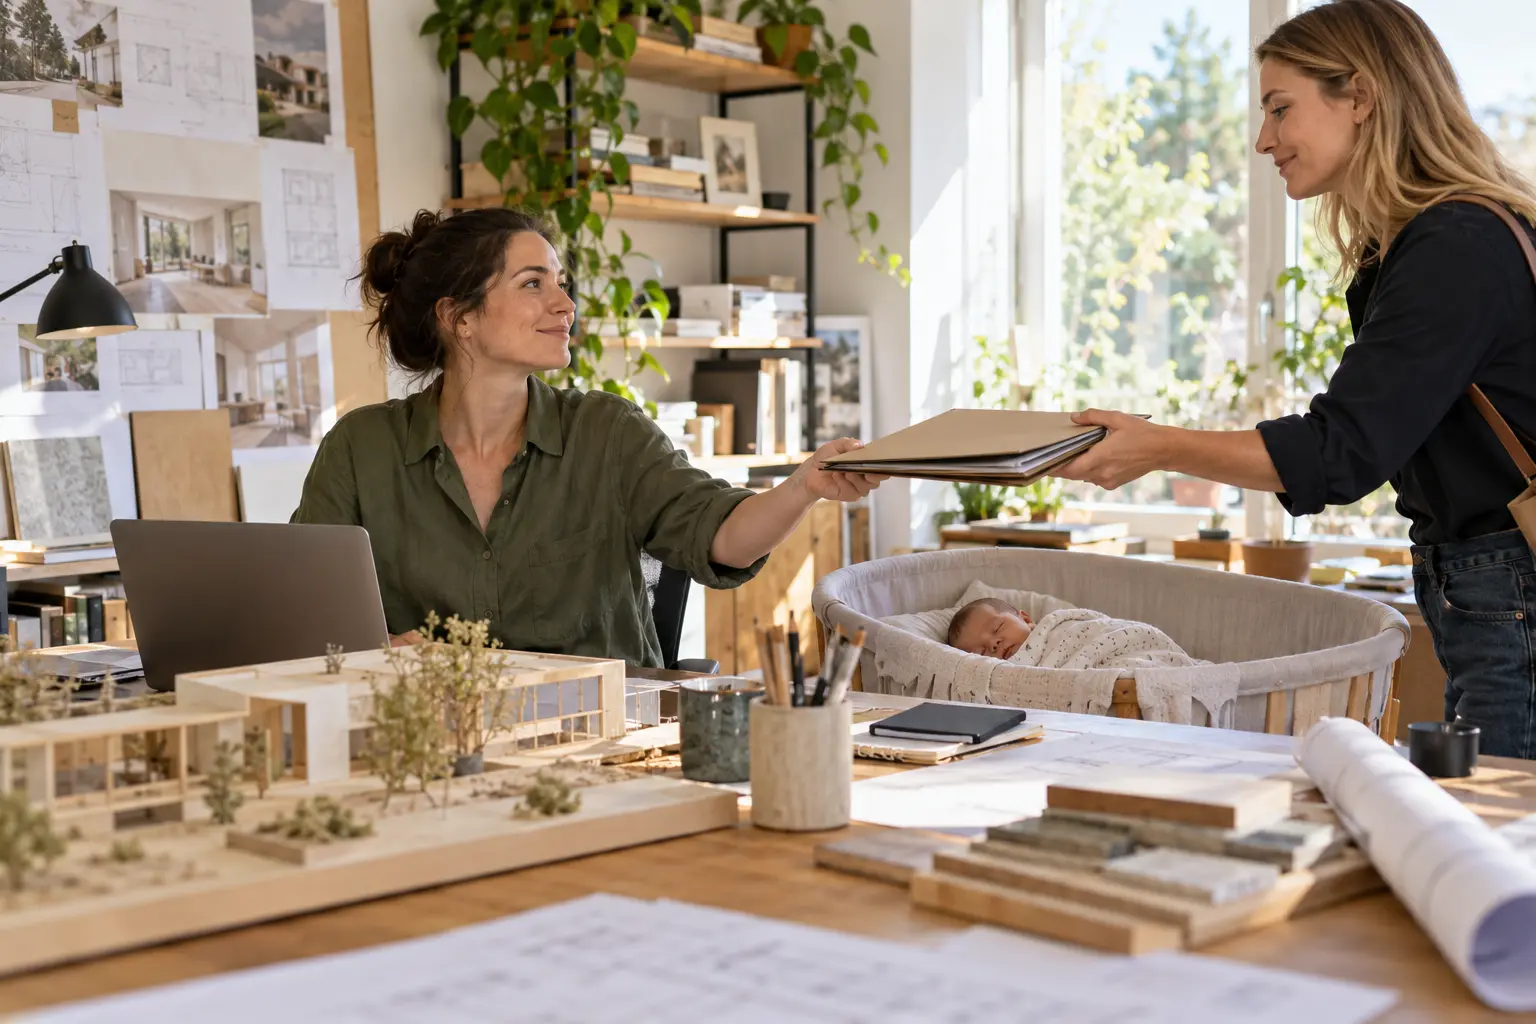
Separate household benefit from business cash flow
A self-employed woman who meets the statutory conditions can receive maternity allowance under the income-compensation system. The official AHV/IV guidance explains the qualifying activity and insurance conditions, the fourteen-week period and compensation based on prior earnings, subject to the applicable maximum. That payment supports personal income. It is not business-interruption insurance and does not automatically cover studio rent, software, loan instalments, employee wages or a locum. The planning problem therefore has two ledgers: the household’s reduced earned income and the enterprise’s continuing fixed costs during a period when the owner’s billable work falls.
Build a leave budget from verified numbers
Request an individual social-insurance review before the expected birth, particularly after a recent start-up, change of legal form or fluctuating income. Estimate the allowance using official information and treat the result as provisional until the compensation office decides. For the business, list fixed monthly costs, contracts that can pause, receivables due, tax and social-security instalments, employee obligations and the cost of a substitute. Add a buffer for an earlier stop or medical complication without assuming a particular benefit. Confirm claim forms, evidence and who can submit them if the owner is unavailable.
A hypothetical architecture studio
Nora runs a sole-proprietor architecture practice and expects a child in March. Her household budget requires CHF 5,800 monthly; the studio has CHF 4,200 of fixed costs before her own drawings. She expects a statutory allowance but does not count it as studio revenue. Six months ahead, she builds a cash reserve, advances two project milestones with client consent and contracts a licensed colleague to supervise a site for eight weeks. She documents authority, professional liability and data access. If the birth date or client schedule changes, the plan can flex. The figures illustrate continuity planning, not an eligibility or benefit decision.
Continuity choices carry real tradeoffs
A substitute preserves clients and deadlines but costs money and can introduce professional-liability or confidentiality risk. Pausing projects saves variable cost but may damage relationships. Hiring an employee improves capacity beyond leave but creates long-term obligations. Private daily-allowance insurance can address defined incapacity before or after maternity, yet waiting periods, underwriting and pregnancy-related exclusions must be reviewed well in advance. A business-interruption policy usually requires an insured cause and should not be assumed to cover ordinary parental leave. The owner must weigh resilience against affordability without relying on overlapping benefits that may not respond.
Prepare a handover that works without you
Name a deputy for banking limits, payroll, urgent client decisions, insurer notices and digital administration. Use least-privilege access and written mandates rather than sharing personal passwords. Create a project register with next action, deadline, contact, contract constraint and escalation rule. Inform key clients of the continuity arrangement while preserving medical privacy. Submit the maternity claim promptly with the required evidence and reconcile the decision with the budget. Keep accounting for any limited work during leave and ask the compensation office how it affects entitlement. Review the plan after return. Statutory protection matters, but operational preparation keeps the enterprise from depending on one exhausted person.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


