
Energy renovation: finance the project without draining every reserve
A heat pump or insulation project needs a cash-flow plan that coordinates grants, mortgage capacity, taxes, contingencies and future maintenance.
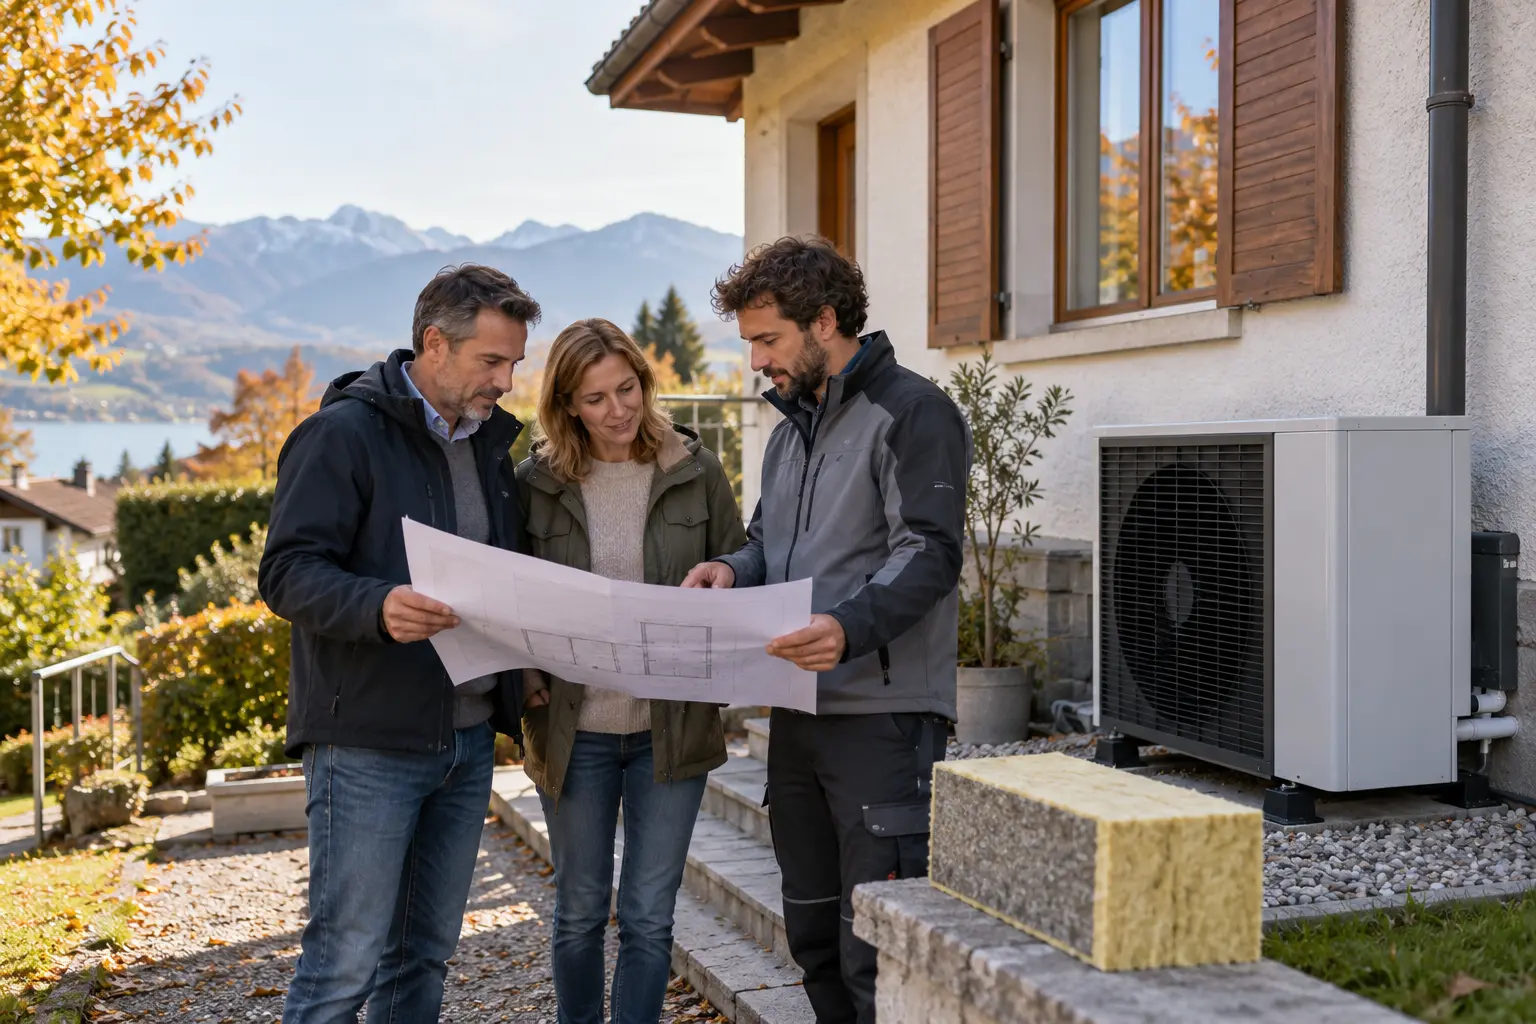
The invoice is only one number
An energy renovation can reduce consumption, improve comfort and protect a building’s usefulness, but its financial path is rarely a single bank transfer. Owners may combine savings, a mortgage increase, a renovation loan, cantonal or municipal support and tax deductions. Timing matters: some grants must be applied for before work begins, invoices arrive in stages and tax effects may occur later. A bank will still examine affordability, property value and lending rules. The public subsidy is not guaranteed until the competent authority approves it, and an expected energy saving should not be treated as certain cash available for debt service.
Build the project in layers
Start with an energy assessment and a scope separating urgent envelope work, heating replacement, optional improvements and cosmetic work. Request comparable quotations that state equipment, interfaces, permits and exclusions. Add planning, electrical changes, disposal, temporary heating and a contingency. Then place each inflow and outflow on a monthly timeline. Keep an emergency reserve outside the project, including enough for mortgage charges and an unrelated repair. Ask the lender what documents support a valuation and when funds can be drawn. Ask the canton which programme applies at the building’s address and obtain written deadlines.
A hypothetical financing stack
Eva and Karim plan CHF 145,000 of insulation and heat-pump work. They could pay CHF 90,000 from cash and seek CHF 55,000 from the bank, but that would leave only CHF 12,000 for household emergencies. Instead they reserve CHF 35,000, request a larger mortgage review, phase one non-essential item and treat a possible grant as reimbursement rather than committed funding. They compare fixed and variable borrowing costs and test the budget at a higher interest rate. If the bank values the completed work less than its cost, they can still reduce the scope. The figures illustrate liquidity planning, not a credit offer.
The tradeoffs are broader than interest
Using savings avoids borrowing interest but sacrifices liquidity and investment options. Increasing the mortgage preserves cash yet raises debt and may require amortisation or a new tranche with different renewal risk. Phasing the work spreads expenditure but can duplicate scaffolding and project management. A package delivered at once may improve technical integration but concentrates disruption and execution risk. Tax deductions vary with the nature and timing of work and the canton; they should be checked with the tax authority. Grants can change, and choosing equipment only for a subsidy may be false economy if maintenance or building compatibility is poor.
A decision gate before signing
Confirm ownership approvals, permits, energy advice, grant application and lender approval before giving an unconditional start order. Match contractor instalments to verified milestones and retain a completion amount where the contract permits. Update building insurance about the new replacement value and equipment, and clarify who covers works in progress. After commissioning, keep warranties, settings, invoices and subsidy decisions in one property file. Recalculate the household reserve and mortgage schedule using actual costs. A sound plan cannot eliminate construction surprises, but it avoids counting the same grant or tax benefit twice and protects the ability to absorb them.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


