
When a dog causes damage: evidence matters before liability is decided
Private liability insurance can be central after an animal incident, but fault, legal liability, exclusions and the deductible still need examination.
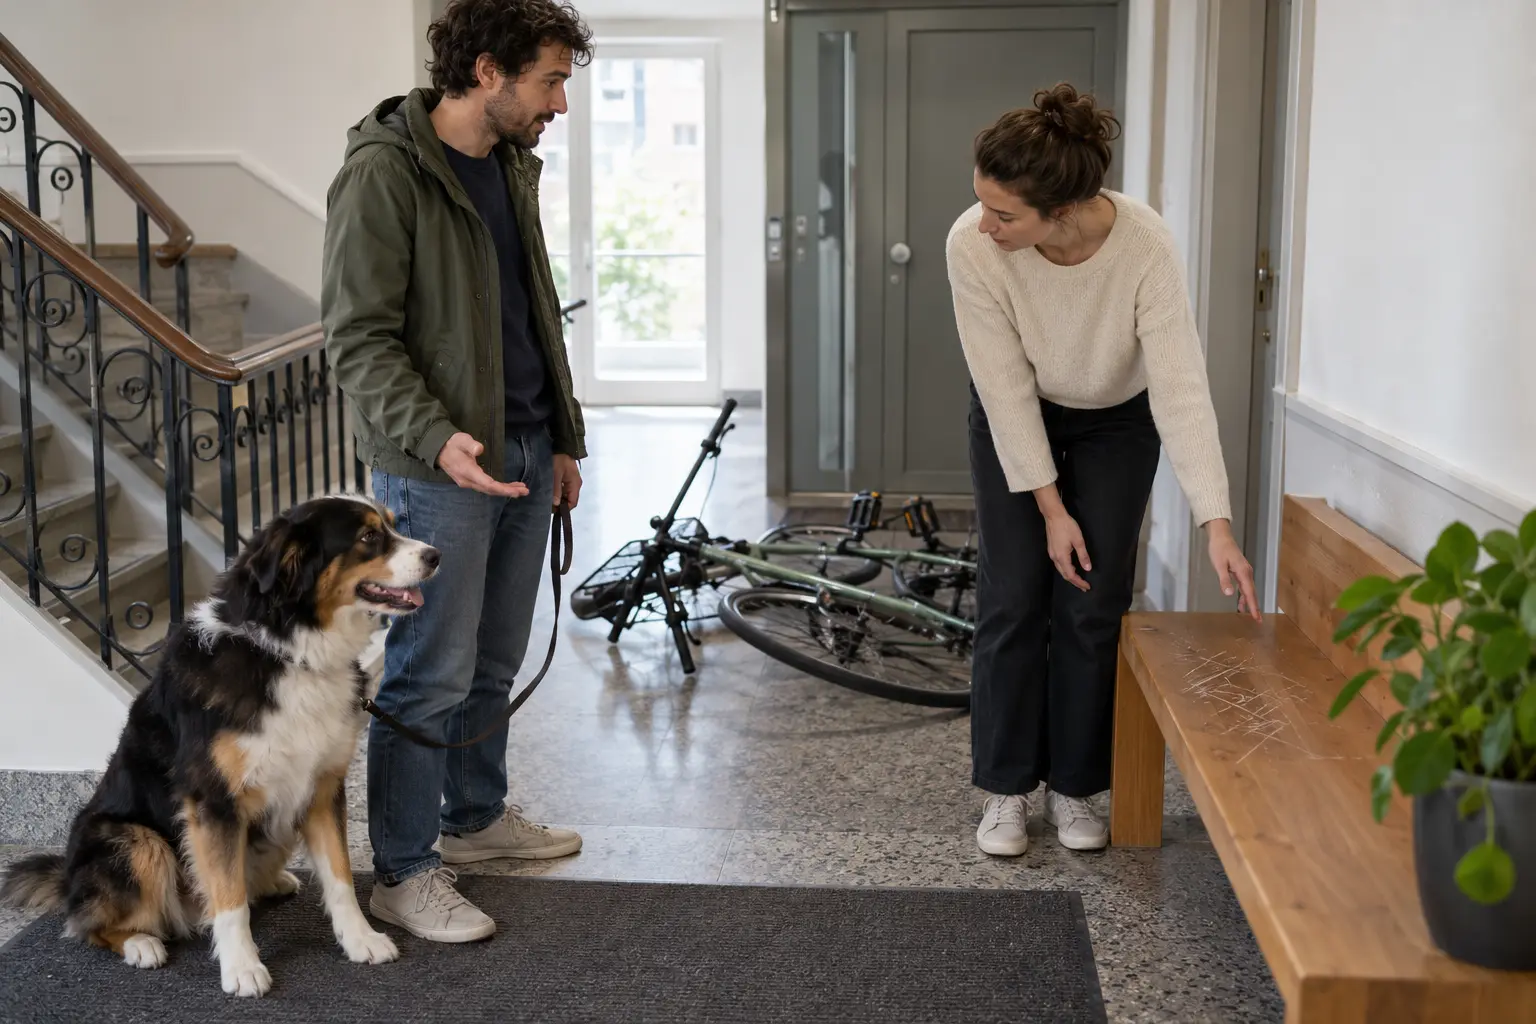
Do not settle the law in the hallway
A dog knocks over a visitor, damages a bicycle or causes another animal to run into traffic. The emotions are immediate, but legal liability still depends on facts and the applicable law. Swiss obligations law contains a specific rule for animal keepers, including the question of whether the keeper exercised the required care. Cantonal rules and the circumstances can also matter. Private liability insurance usually examines covered legal liability, defends against unjustified demands and pays justified claims within the policy. It is not a blanket promise that every cost connected with a pet will be reimbursed.
Preserve a neutral incident file
First secure people and animals and call emergency services if necessary. Record the time, place, weather, leash situation and sequence without speculating. Photograph the area and damage, identify witnesses and exchange contact details. For an injury, encourage prompt medical documentation. Do not repair or discard damaged property before the insurer can assess it, except to prevent further harm. A calm written account produced on the same day is more useful than competing memories weeks later. Avoid signing an admission, paying an arbitrary cash amount or posting accusations online; notify the insurer and let it assess legal responsibility.
A hypothetical bicycle claim
Milo slips his lead in the entrance of an apartment building and bumps a neighbour’s parked e-bike, which falls against a wooden bench. The owner photographs the lead, doorway, bicycle and marks, records the neighbour’s invoice estimate and reports the event. The neighbour initially requests the price of a brand-new bicycle. The insurer asks whether repair is possible, what the pre-loss value was and whether the building owner also claims for the bench. It may accept some items, dispute others and apply the contractual deductible. The example illustrates claim handling; it does not decide whether the keeper met the statutory care standard.
Coverage boundaries worth checking
The policy may define which household members are insured, whether particular animals or activities are excluded, and how gross negligence, professional use or custody of another person’s property is treated. Damage to the policyholder’s own belongings is not third-party liability. Some cantons impose dog-liability or training requirements, but these are not identical across Switzerland. A high sum insured can protect against severe injury claims, while a high deductible reduces small-claim usefulness. Reporting every scratch may affect administration or claims history; failing to report a potentially serious injury can be much worse. The sensible choice follows the policy and severity.
Prepare before the next walk
Read the liability section and note the insurer’s emergency and claims contacts. Confirm that every household dog is declared when required and that any canton-specific obligation is met. Keep vaccination, training and ownership records together. Use appropriate leads, gates and supervision for the setting, not merely the minimum rule. If an incident occurs, mitigate damage, document, notify and forward every demand unanswered to the insurer. Keep receipts for urgent measures and the final settlement. Insurance transfers defined financial risk; prevention and responsible handling remain with the keeper, and no policy can guarantee that a dispute will be resolved without inconvenience.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


