
Total loss: understand new-value and current-value compensation before buying the car
Casco labels sound simple, but the payout after theft or total loss depends on the policy’s schedule, vehicle value, deductible and financing balance.
Liability and casco answer different questions
Motor third-party liability is compulsory and responds to damage caused to others. Damage to the insured car, theft, hail or collision requires the appropriate casco cover and remains governed by the contract. When repair is uneconomic or the car is missing, the wording used to value a total loss becomes decisive. “New value”, “supplementary current value” and “current value” are not universal amounts. Insurers use their own time schedules, percentages, mileage rules, accessories treatment and deduction clauses. A quotation should therefore be read alongside the general and special conditions, not compared by premium and marketing label alone.
Reconstruct the payout waterfall
Ask what triggers a total loss, which valuation table applies in each vehicle year and whether the basis is list price, purchase price or market value. Then identify deductions for deductible, unrepaired prior damage, tyres, high mileage, unpaid premium or salvage. Factory options, later accessories and seasonal wheels may have separate limits. Leasing and loan contracts add another layer: the insurer may pay the owner or finance company, and the settlement may not equal the outstanding balance. Gap cover can address defined shortfalls, but its exclusions and duration need the same scrutiny.
A hypothetical hail loss
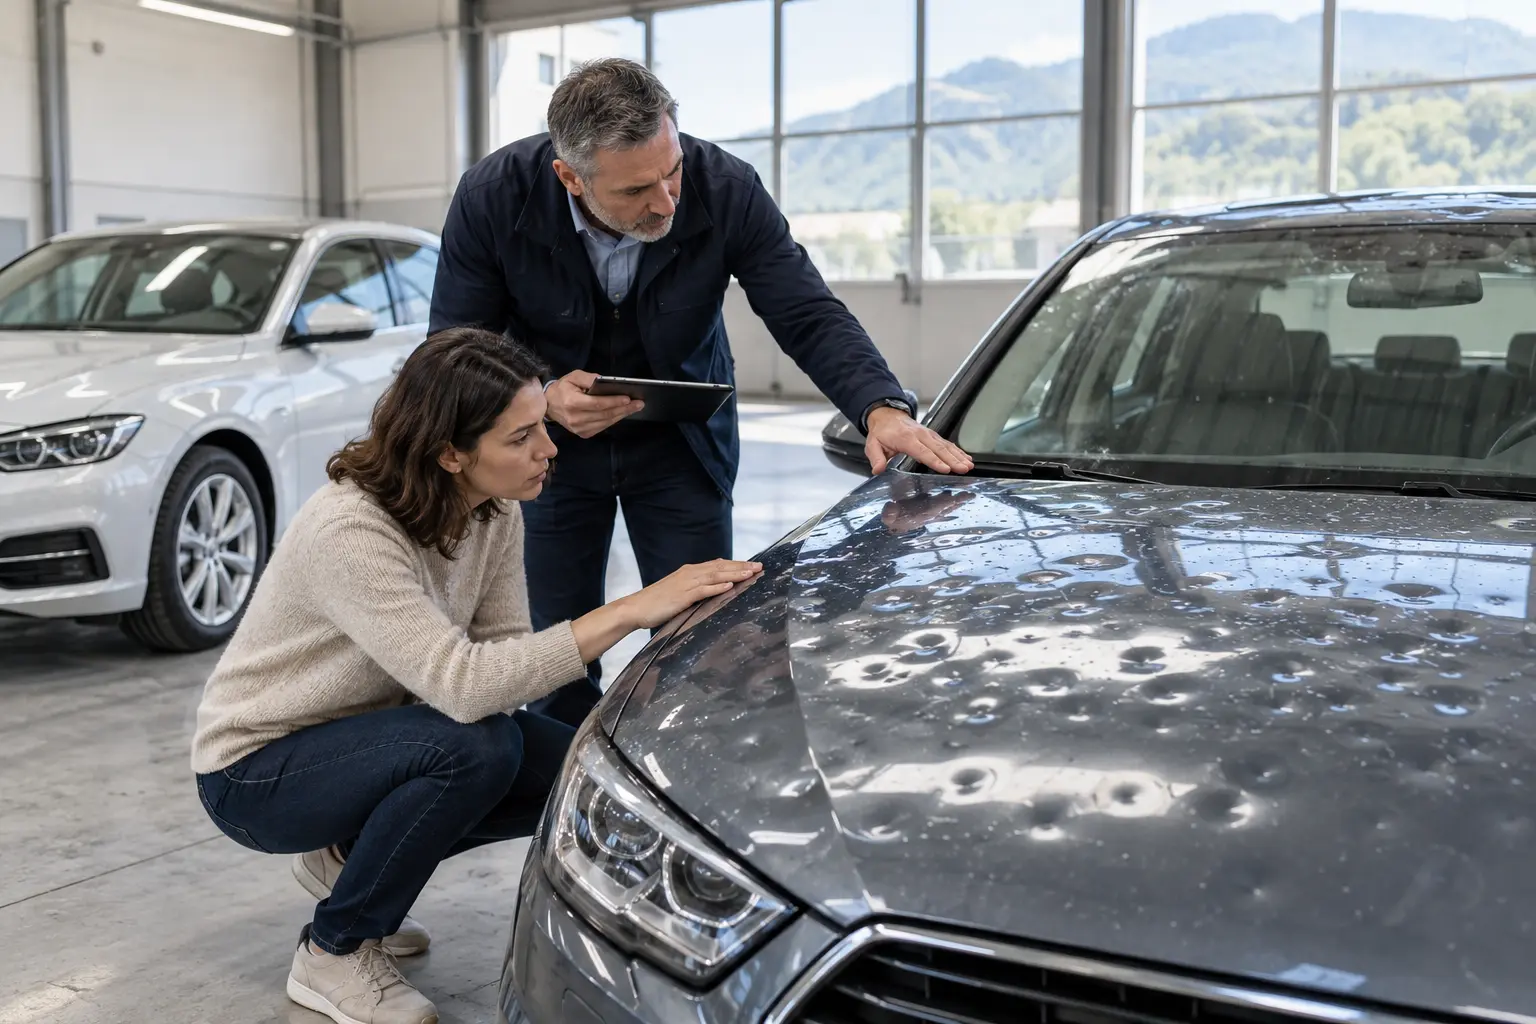
Ana buys a three-year-old electric car for CHF 42,000 with a CHF 30,000 loan. Eighteen months later, severe hail makes repair uneconomic. Her policy uses a supplementary-current-value table, applies a CHF 1,000 deductible and limits non-factory accessories. The adjuster calculates the insured value under that table, not the price of a comparable new model. If the result were CHF 34,000, the lender would be repaid first and the remainder would go according to the finance agreement. If the balance exceeded the settlement, Ana could still owe money. The numbers are illustrative; only the policy and assessment determine the claim.
Pay for the period of real exposure
Enhanced compensation is most valuable when depreciation is rapid and financing remains high. It costs more and may provide little benefit once the schedule approaches ordinary current value. A higher deductible reduces premium but increases the cash needed after a loss. Full casco may be required by a leasing agreement even when the driver would otherwise self-insure collision damage. Electric-vehicle owners should also examine battery, charging cable and recovery provisions rather than assuming the vehicle label solves them. The sensible design follows replacement ability, financing and risk tolerance, and is reviewed as the car ages.
Create a one-page vehicle record
Keep the purchase contract, finance balance, registration, option list, accessory receipts and photographs. Mark the policy year in which the valuation method changes and set a renewal reminder. Ask the insurer to explain a worked total-loss calculation in writing, including VAT and deductible. After damage, prevent further loss, photograph before moving the vehicle if safe, report promptly and do not approve disposal until ownership and salvage are clear. Compare the settlement statement with the contractual table and finance payoff. Insurance can fund a defined value after an insured event; it cannot guarantee a like-for-like replacement in every market.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


