
A small pollution event can expose the gaps in business liability
A spill may trigger emergency containment, cleanup, third-party damage and public-law costs that do not all follow the same insurance clause.
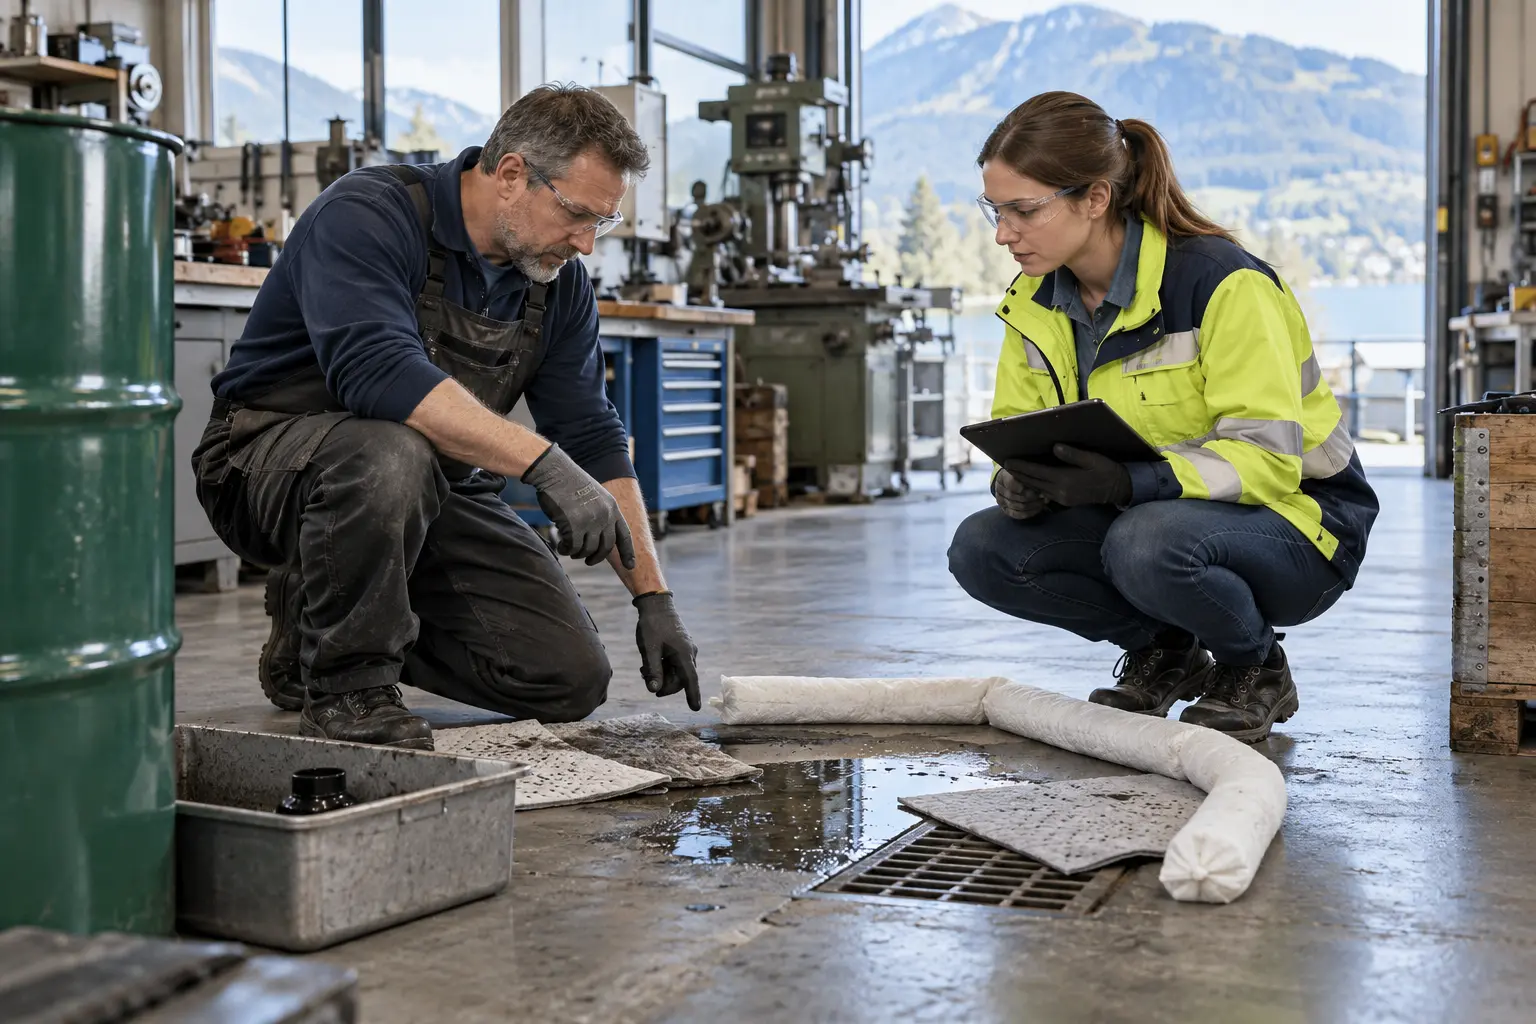
One spill creates several cost categories
A leaking drum near a drain may require immediate containment, soil or water testing, disposal, authority communication, restoration of a neighbour’s property and defence against a claim. General business liability mainly addresses covered legal liability to third parties. It may distinguish sudden accidental pollution from gradual contamination and may exclude cleanup of the company’s own site, regulatory orders or known conditions. Environmental impairment extensions can broaden protection, but names and scopes differ. The company must therefore map each cost to the policy wording rather than assume that “liability” pays every invoice after an environmental incident.
Response speed and evidence are inseparable
Protect people first and stop the source if this can be done safely. Use spill kits, block drains and call emergency services or the competent authority when required. Photograph the source, pathway and containment before cleanup changes the scene; record material, estimated quantity, time, weather and responders. Preserve safety data sheets, waste manifests and contractor invoices. Notify the insurer immediately and ask whether specialist contractors require approval, without delaying mandatory action. Do not minimise the event or speculate about blame. A clean timeline helps authorities, experts and insurers distinguish emergency mitigation from later remediation and third-party damage.
A hypothetical coolant leak
A precision workshop discovers that a hose released coolant overnight. Most liquid stayed on the sealed floor, but a small amount reached a yard drain shared with the neighbouring property. Staff deploy absorbent barriers and call the fire service. Tests find no downstream contamination, yet the drain must be cleaned and production stops for a day. The liability insurer examines potential third-party and defence costs; property or interruption insurance examines the shutdown; the company may retain its own-site cleanup and deductible. The exact allocation depends on cause, timing and clauses. The example shows why one event should be notified across relevant policies.
Prevention competes with hidden accumulation
Secondary containment, drain maps, inspections and staff drills cost money and time. Yet gradual seepage can remain unnoticed until cleanup is far more expensive and may fall outside cover. A broad environmental extension adds premium but can address a severe balance-sheet risk; a high deductible may still be rational for a firm able to fund small incidents. Contractual liability to a landlord or client may exceed ordinary legal liability and be excluded. Acquisitions and old sites add historical contamination that a new policy may not accept. Risk transfer works best after honest environmental due diligence, not as a substitute for it.
Run a pollution tabletop exercise
Mark storage, drains, shutoffs and sensitive neighbours on a site plan. Inventory substances and maximum quantities, inspect bunds and keep spill equipment accessible. Ask the broker or insurer in writing about sudden and gradual pollution, own-site cleanup, authority costs, transport, subcontractors and business interruption. Simulate a 10-minute response and correct unclear responsibilities. Store authority and insurer numbers offline. After any incident, retain samples and records according to professional advice and document corrective work. No policy guarantees that an authority will accept remediation or that every environmental cost is insurable; a rehearsed response reduces harm and preserves the evidence needed for a coverage decision.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


