
Liability, partial casco, collision: separate three different financial risks
Car insurance becomes clearer when you separate harm caused to others from damage to your own vehicle. Start with the loss you need to finance, then identify the coverage that addresses it.
The question that matters
Car insurance becomes clearer when you separate harm caused to others from damage to your own vehicle. Start with the loss you need to finance, then identify the coverage that addresses it.
Build the evidence
Record ownership, financing arrangements, replacement value and ability to absorb repair costs. Swiss motor liability is a compulsory foundation, while own-vehicle damage requires examination of additional cover and any financing obligations.
A hypothetical case
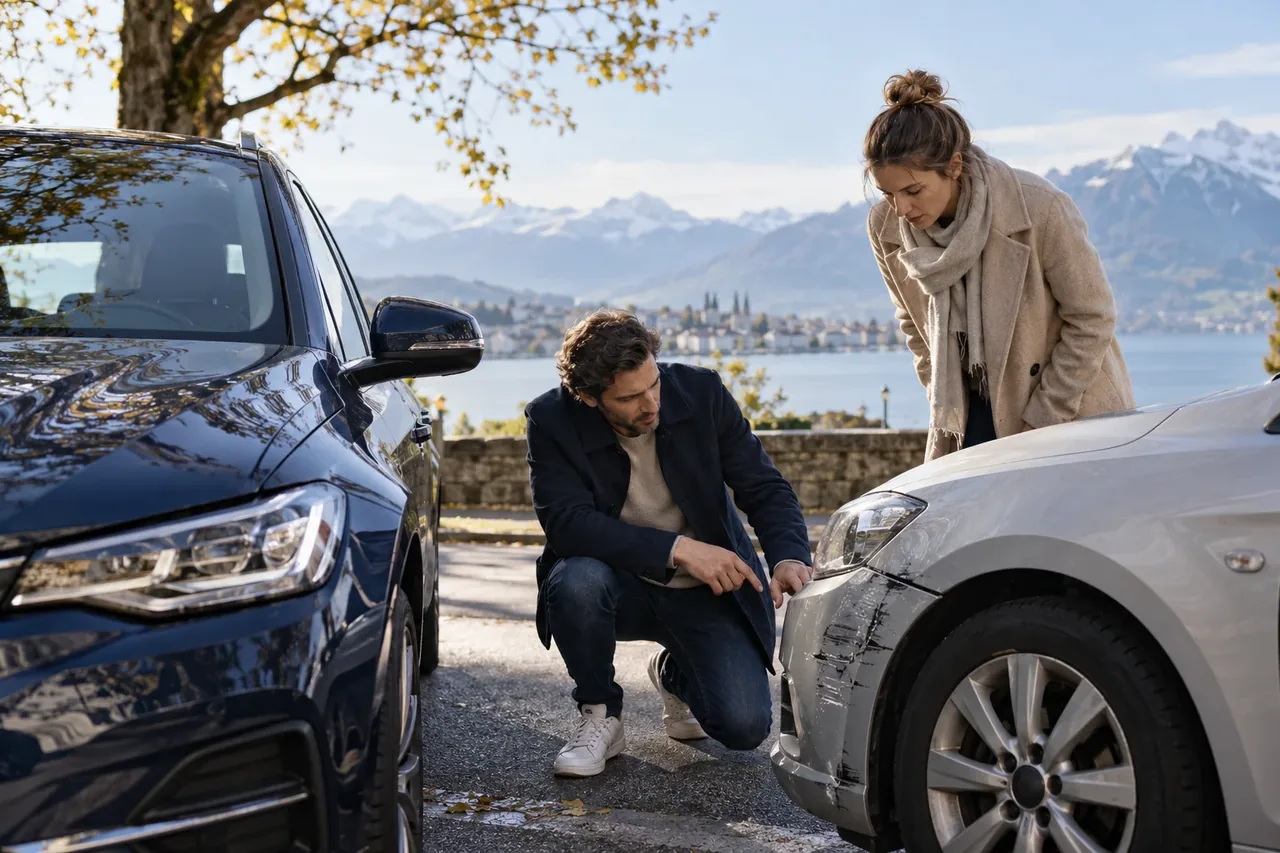
In an illustrative collision you cause, the other driver’s damage and your own repair bill are separate losses. Liability does not become own-car collision insurance simply because you paid a comprehensive-looking premium.
Compare the right conditions
Compare covered events for partial casco, collision deductibles, theft conditions and settlement valuation. Ask whether parking damage is separate and whether selected garage arrangements affect benefits. Use matching deductibles when comparing prices.
Limits and uncertainties
Coverage names do not establish identical terms across providers. A vehicle’s age alone does not decide whether collision cover is useful: its replacement cost and your liquidity also matter. Exclusions and claims conditions require reading.
Stress-test three losses separately
Imagine three independent situations: you hit another car, hail dents your bonnet and your vehicle is stolen. Write separate columns for damage to other people, damage to your car and the costs of remaining mobile. Ask the insurer to identify the relevant clause for each rather than answering that the car is fully insured. In the collision example, add a fourth question if your own gate is damaged: your property is not automatically equivalent to a third party’s property. The TCS product page illustrates why named extensions and event definitions matter, but its terms are not a market-wide standard. For each scenario, show the deductible, settlement valuation and any replacement-car entitlement. Keep the estimated financial consequence separate from the estimated probability. A rare total loss can be unaffordable even when ordinary repairs would fit your budget. Conversely, small recurring scratches may not justify buying every available option.
Choose retained risk deliberately
For an older paid-off vehicle, estimate the replacement car you would realistically buy, not simply its original purchase price. Compare that amount with accessible savings and your dependence on driving to work. Removing collision cover changes who finances damage you cause to your own car; it does not reduce that replacement need. Retaining partial casco can answer a different set of events, subject to the wording. Ask for a quotation with and without each layer while holding the other assumptions fixed. Do not compare a liability-only premium with a comprehensive premium as though the difference represents avoidable waste. If financing requires particular cover, resolve the contractual requirement first. Store the final layer map with the vehicle documents and revise it after a major change in value, ownership or use. The objective is a defensible budget and continuity of transport, not a universal rule based on the car’s birthday.
Your practical next step
Ask for quotations showing each coverage layer separately. Request illustrations for a caused collision, theft and unidentified parking damage. Decide what loss you could comfortably pay yourself before removing a layer.
Sources and further reading
Original Clearwise analysis. External reporting provides context; rules and contract terms must be verified with the competent authority or provider. Some press articles may require a subscription.
Apply this to your situation
Compare your actual documents and clarify what matters before making a commitment.
Request a free consultationGeneral guidance, not a binding quote or personalised legal, tax or investment advice. Examples are hypothetical and results are not guaranteed.


